A budget that works until the month changes
At the start of the month, the plan often looks settled: bills are covered, savings has a target, and the remaining money appears available for ordinary spending. Then a car repair, school fee, or higher grocery bill changes the balance. A budget built around neat categories can become difficult to trust once the calendar moves beyond the first week.
That tension separates the two approaches. Zero-based budgeting assigns each dollar a purpose, making an unexpected expense visible immediately—but it may require repeated adjustments. A traditional budget leaves more room to absorb changes, though unassigned money can quietly disappear into discretionary spending. The better method depends less on mathematical precision than on how often income, expenses, and priorities refuse to stay predictable.
Start with the spending style you actually have
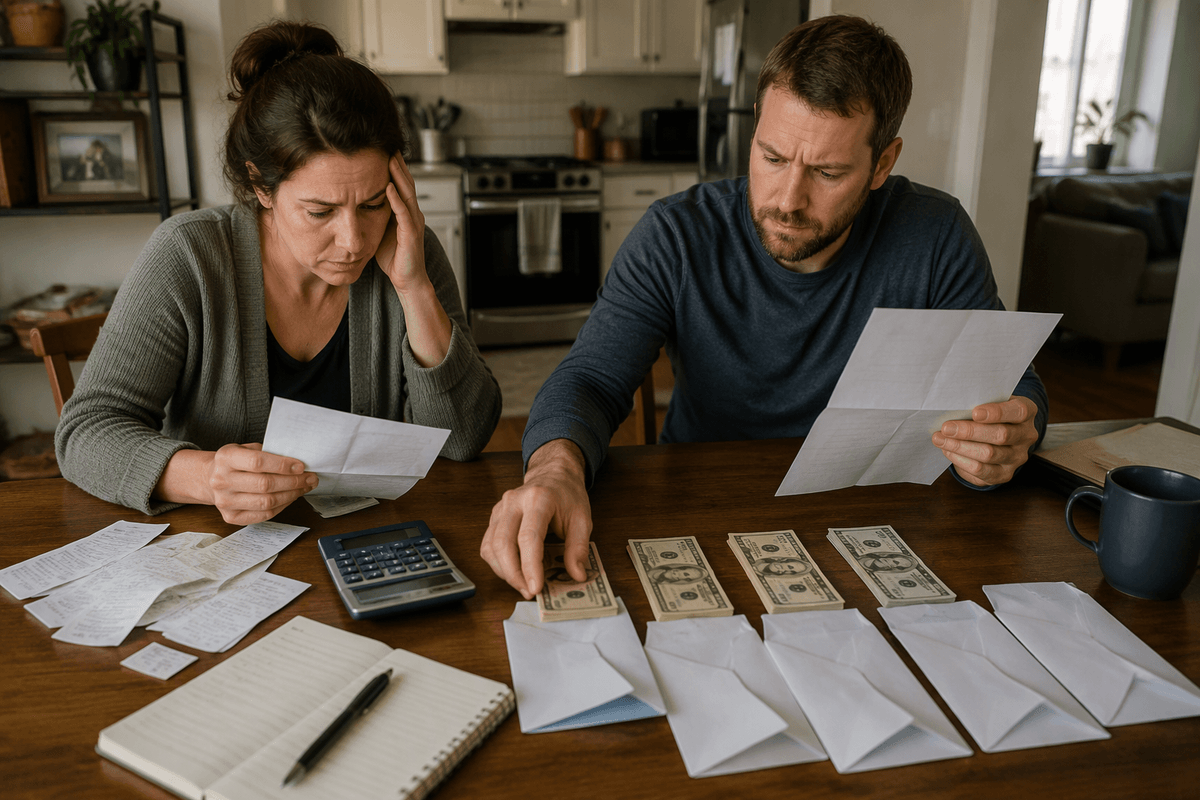
The first useful question is not which budget looks more disciplined on paper. It is what usually happens after income arrives. Some households spend from a short list of fixed bills, savings, and weekly allowances. Others move money between categories as prices change, plans appear, and irregular costs arrive. A method that ignores those habits can create extra work without improving decisions.
For a household with steady pay and predictable expenses, assigning every dollar may expose small leaks before they become larger problems. The constraint is time: each new charge may require a category change, especially when several accounts or shared expenses are involved. A more flexible budget may suit households with variable income or frequent surprises, because broad spending limits can absorb movement. Its weakness is less visible drift; money left “available” can be spent before a repair, annual bill, or savings transfer is covered.
Past spending records usually reveal the better starting point. If categories are routinely adjusted, flexibility may be realistic rather than careless. If money regularly vanishes without a clear reason, tighter allocation can provide the visibility the current routine lacks.
Zero-based control reveals where income goes
Once the spending pattern is clear, assigning income becomes a test of what the household actually values. In a zero-based budget, the month begins with a finite amount of money and ends only when every dollar has a destination: housing, food, debt payments, savings, irregular bills, or planned spending. The result is not necessarily lower spending. It is clearer evidence of where spending is being chosen rather than simply allowed.
That visibility matters when an account balance looks healthy but several obligations are approaching. Setting aside money for car maintenance, annual insurance, or holiday costs prevents those expenses from competing with the next paycheck. It also exposes trade-offs early. Increasing restaurant spending may mean reducing entertainment, delaying an extra debt payment, or using less for savings. The constraint is maintenance: a purchase that does not fit the plan must be recorded and funded by moving money elsewhere.
For households that often wonder where the month’s income went, this control can be more valuable than convenience. But precision has a cost. If categories become too detailed, or every small change feels like administrative work, the budget may be abandoned before its visibility produces better decisions.
Traditional budgeting bends when life gets unpredictable
That maintenance burden becomes more noticeable when the month refuses to follow its forecast. A traditional budget usually groups spending into broad limits—food, transport, personal spending, and savings—rather than assigning every dollar in advance. When groceries cost more or a medical bill arrives, money can be shifted within those limits without rebuilding the entire plan.
The flexibility is useful, but it is not free. A household may cover a $600 repair by reducing dining out, entertainment, or general spending, yet the adjustment can remain invisible if those categories are loosely tracked. The budget still appears balanced while savings progress slows or a future bill loses its funding. The constraint is judgment: broad categories absorb shocks only when someone notices which priority is being sacrificed.
Traditional budgeting also handles irregular income more comfortably when the exact amount arriving is uncertain. Instead of assigning every dollar before payday, the household can fund essentials first and revise discretionary limits afterward. That reduces setup effort, but it weakens advance control. When surprises happen often, this trade-off may be reasonable; when spending already drifts, flexibility can become permission to postpone difficult choices.
Which method costs more effort each month?
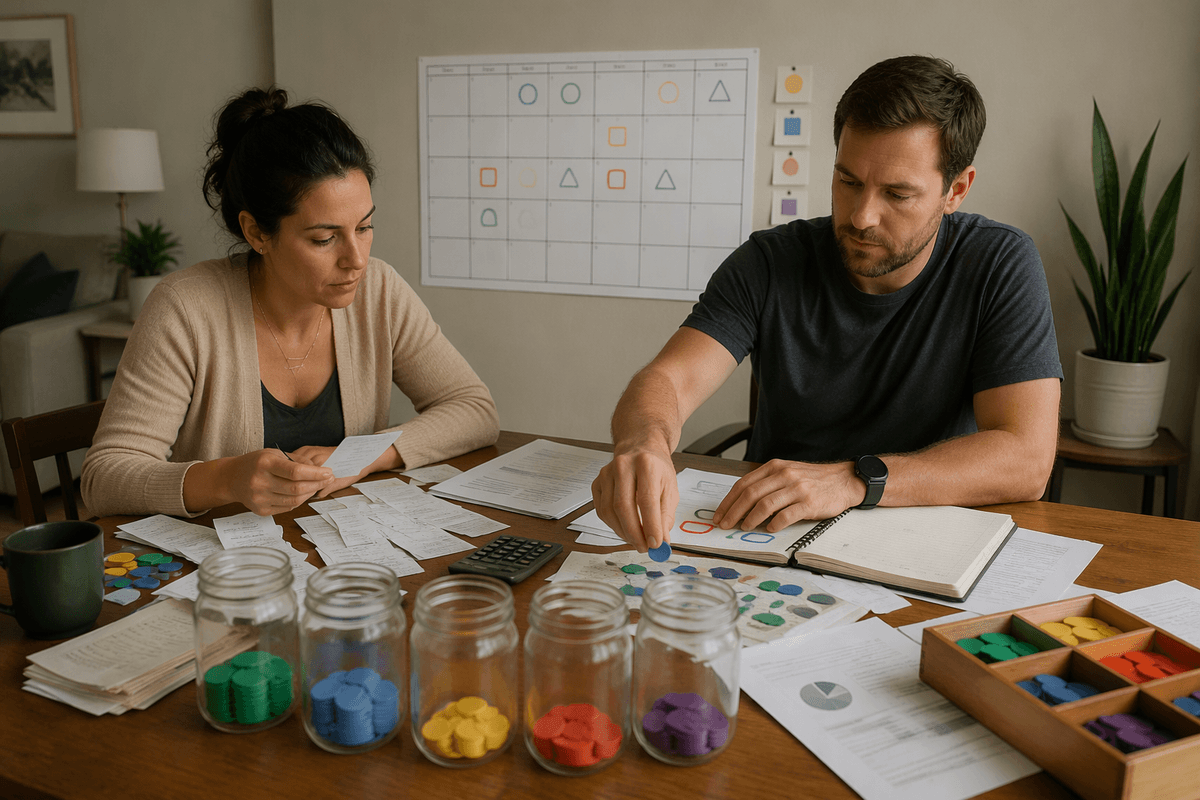
The difference becomes clearest during ordinary maintenance, not during setup. Zero-based budgeting usually takes more attention after the plan is created: transactions must be categorized, overspending corrected, and unused money reassigned when priorities change. That effort may take only a few minutes at a time, but it becomes tiring when several accounts, irregular bills, or shared purchases complicate the record.
A traditional budget reduces that monthly handling because broad limits do not need constant rebalancing. The trade-off appears later, when a category runs over or an annual expense arrives without enough money reserved. Finding the shortfall may require reviewing several weeks of purchases, which can take longer than making smaller adjustments in a zero-based plan. The real cost depends on the household’s recurring friction. A detail-oriented household may find zero-based budgeting manageable, while someone who avoids tracking transactions may get better results from fewer categories and a scheduled monthly review.
When priorities shift, what survives the plan?
A change in priorities tests whether the budget reflects real choices or only the original forecast. A zero-based plan makes the adjustment explicit: if a family redirects $200 toward a medical bill, that amount must come from dining out, savings, debt repayment, or another category. Nothing disappears from view. The constraint is emotional as well as administrative, because reducing a valued goal can make the plan feel like a record of setbacks.
A traditional budget may absorb the same change with less rearranging. Broad spending limits can be tightened while the household keeps moving, but the cost may be harder to identify. Savings could fall gradually, or an annual expense may become underfunded without a clear decision being recorded. This flexibility works best when priorities are reviewed regularly rather than assumed to remain stable.
Neither method protects every goal. Zero-based budgeting preserves visibility; traditional budgeting preserves room to maneuver. The stronger plan is the one that makes changing priorities noticeable without demanding more tracking than the household can sustain.
Choose the friction you can keep managing
The choice is less about finding the perfect system than identifying which failure is easier to correct. Zero-based budgeting suits a household willing to review transactions and move money when plans change. Its friction is frequent attention, especially when income varies or expenses are shared. Traditional budgeting suits a household that needs breathing room and can tolerate less detail. Its friction appears when broad categories hide slow overspending or leave irregular bills unfunded.
A workable trial can settle the question: use one method for two or three months, then check whether savings, essential bills, and discretionary spending stayed visible without constant frustration. If the process is repeatedly skipped, its theoretical control has little value. The better budget is the one that still gets updated after an expensive, inconvenient month.