The Share Price Looks Cheap—Until You Compare Businesses
A low share price can make one company look like the obvious bargain. Then the comparison reaches a rival with a higher-priced stock, and the quick judgment starts to weaken. Share price alone says little about the value of the businesses being compared because companies issue different numbers of shares. A $20 stock may represent far more equity than a $50 stock, or far less.
Market capitalization provides the first useful adjustment: it multiplies the share price by shares outstanding. That reveals what the stock market is assigning to the company’s equity, but not necessarily to the operating business itself. Debt, cash, and other claims can make two companies with similar market capitalizations materially different investments.
Market Capitalization Starts With the Equity Story
That equity figure begins with a simple calculation, but its meaning depends on what the shares represent. Market capitalization is the share price multiplied by the number of shares outstanding. If a company has 100 million shares trading at $30, the market is placing a $3 billion value on its common equity. That is the portion attributable to shareholders, not a complete price tag for every financial claim on the company.
The number also reflects the market’s expectations about future earnings, growth, risk, and management decisions. A rising market capitalization may signal stronger expected cash flows, but it can also result from a temporary surge in investor enthusiasm. Conversely, a falling figure may reflect genuine deterioration or simply a broad market selloff. Timing creates a practical constraint: the calculation changes every trading day, while the underlying business changes more slowly.
Share counts introduce another complication. Stock options, restricted shares, and convertible securities may eventually increase the equity base, making a basic market-cap comparison look more favorable than the diluted reality. Even after adjusting for those claims, market capitalization answers a limited question: what is the market currently assigning to the shareholders’ stake? The next comparison must account for the financing attached to the business itself.
Enterprise Value Reframes the Same Company
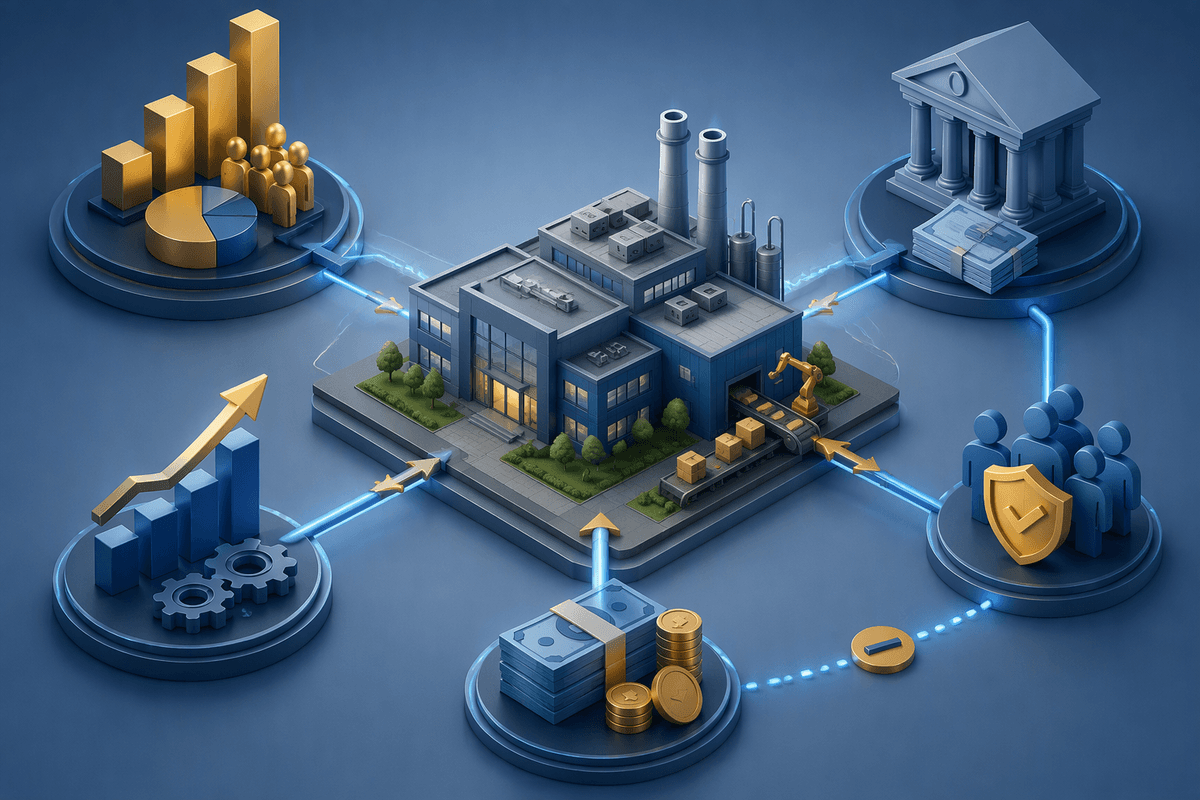
That broader price tag is what enterprise value is designed to approximate. It starts with market capitalization, then adds debt and other debt-like claims, while subtracting cash and cash equivalents. The result is an estimate of what it would cost to acquire the operating business after accounting for financing already in place. A company with $3 billion of equity, $1 billion of debt, and $400 million of cash would have an enterprise value of roughly $3.6 billion.
The adjustment changes the comparison because shareholders are not the only parties with an economic claim. Lenders expect repayment before common shareholders receive the remaining value, while excess cash can reduce the effective cost of taking control of the business. Two firms with identical market capitalizations may therefore require very different amounts of capital to acquire and operate. Ignoring that difference can make a heavily indebted company appear cheaper than a financially stronger rival.
Enterprise value is especially useful when comparing operating performance through measures such as EV-to-EBITDA, because the numerator reflects both debt and equity financing. It is not frictionless, though. Debt balances may include leases or unusual obligations, and cash may not all be available for general use. The calculation can also become misleading for banks and other financial firms, where borrowing is part of the operating model rather than merely a funding choice.
Debt and Cash Can Reverse the Apparent Bargain
The difference becomes most visible when two companies appear equally valued on an equity basis. Suppose each has a market capitalization of $5 billion. One carries $2 billion of debt and holds $200 million in cash; the other has only $500 million of debt and $1 billion in cash. Their enterprise values would be about $6.8 billion and $4 billion, respectively. The first company may look cheaper on a price-to-earnings measure, yet it represents the more expensive operating business once its financing is included.
Cash can change the judgment just as sharply, although not every dollar deserves equal treatment. Restricted funds, foreign cash, or money needed to support daily operations may not be freely available to an acquirer. Debt also brings more than a balance-sheet number: interest expense reduces future earnings, refinancing can become costly when rates rise, and repayment deadlines create timing risk. A valuation that seems attractive before those obligations are considered may offer little margin of safety afterward.
The practical mistake is treating enterprise value as a correction that always makes a company look more expensive. Net cash can lower it substantially, while heavy borrowing can push it well above market capitalization.
Which Measure Fits the Question You Are Asking?
The right measure depends on what the comparison is trying to answer. If the question is how much value belongs to common shareholders, market capitalization is the cleaner starting point. It is also useful when examining shareholder returns, stock-based compensation, or a price-to-earnings ratio, because those measures focus on equity investors. The constraint is that this view can hide financing pressure. A company may show a modest equity value while carrying debt that limits future distributions.
Enterprise value fits a different question: what value is attached to the operating business after debt and cash are considered? It is usually more informative when comparing companies with different capital structures or using EV-to-EBITDA. Yet that comparison can create its own friction when cash is restricted, leases are material, or earnings are temporarily depressed. Neither measure should be selected because it produces the more favorable result. The useful choice follows the decision: shareholder value calls for market capitalization; operating-business comparisons often call for enterprise value.
Neither Number Captures the Whole Business
Even a careful adjustment leaves important questions unanswered. Market capitalization can reflect investor expectations that are difficult to separate from temporary sentiment, while enterprise value depends on judgment about which debts, leases, and cash balances truly belong in the comparison. A large cash balance may support the business rather than reduce its effective price, and a low debt figure may conceal refinancing pressure or obligations outside the headline balance sheet.
Operating quality creates another gap. Neither measure shows whether earnings are durable, whether capital spending will absorb cash, or whether management can turn revenue into returns. The figures are useful starting points, but they do not remove uncertainty. Valuation becomes more reliable when the chosen measure is tested against cash flow, balance-sheet risk, and the business’s ability to sustain its results.
Use Both Measures Before Calling Valuation Attractive
The comparison is strongest when both figures are calculated before the valuation judgment is made. Market capitalization shows what shareholders are paying for the equity; enterprise value shows what the operating business represents after debt and cash are included. Looking at only one can distort the conclusion, especially when leverage, excess cash, or diluted shares materially change the result.
A company may appear inexpensive on a price-to-earnings basis yet carry enough debt to weaken its flexibility. Another may look costly by market capitalization but hold substantial usable cash and require less capital to support operations. The remaining constraint is business quality: neither measure proves that earnings will last. Valuation becomes more credible when both numbers point to a reasonable price and the balance sheet does not quietly overturn the bargain.