The Grocery Trip That Breaks Your Budget
The receipt looks manageable until the groceries are put away. A few fresh items, a larger package chosen for its lower unit price, and one tired-day convenience purchase can push a solo shopper past the amount set aside for the week. Nothing feels extravagant on its own. The mismatch appears later, when rent, utilities, or a planned meal compete with what is left in the account.
For one person, grocery spending is shaped by more than hunger. Prices change, schedules shift, and packages often contain more food than one household can use. A useful budget has to account for those pressures without treating every purchase as a mistake. The first step is seeing which trips quietly break the limit and why.
Start With What You Actually Spend
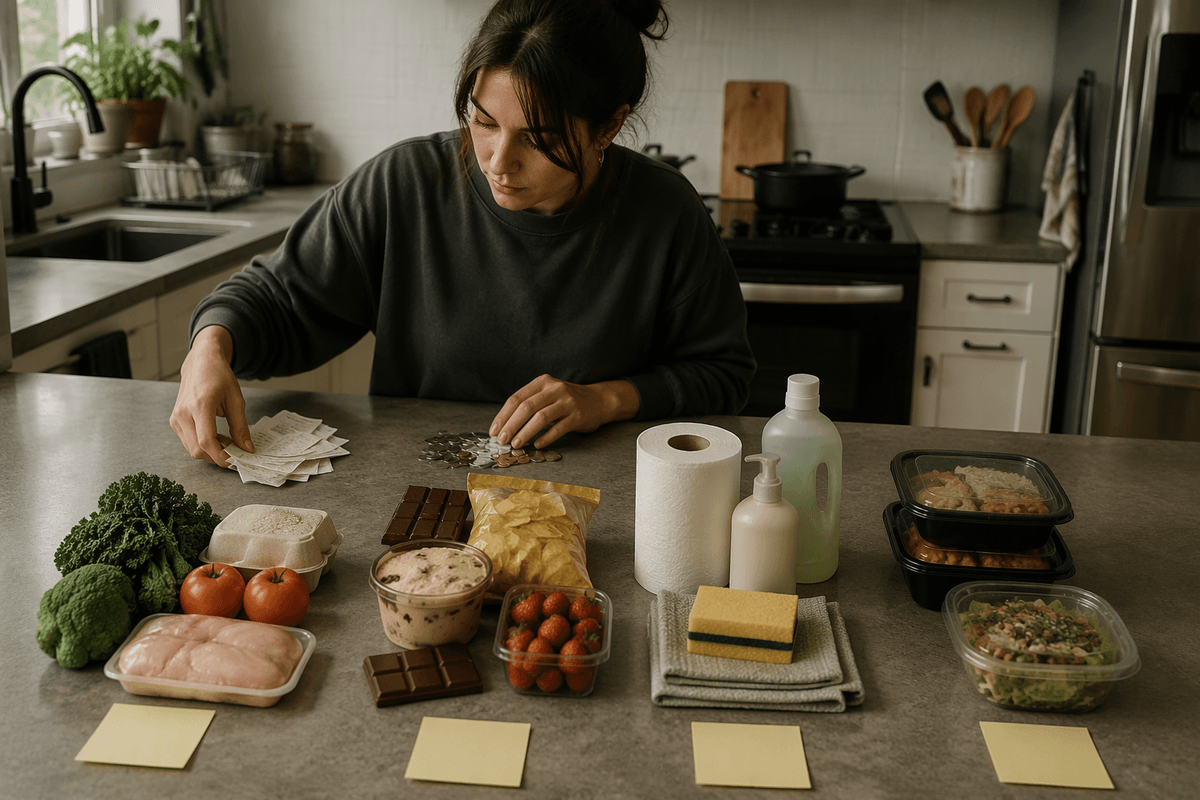
Before setting a weekly limit, collect the last three or four grocery receipts and include delivery fees, small convenience-store stops, and meals bought because food at home was unusable or inconvenient. The total may be higher than expected, but it gives a more reliable starting point than a number borrowed from a budget template. A month with a stock-up purchase can distort the picture, so note what was unusual rather than treating it as a permanent habit.
Then separate the spending into a few practical groups: basic meals, preferred foods, household staples, and convenience purchases. This shows where the money is doing necessary work and where timing or fatigue is making the decision for you. The exercise also exposes constraints a one-person household cannot avoid, such as buying a full package when only two servings are needed. The first budget does not need to be perfect. It needs to describe real behavior closely enough that the next adjustment is based on evidence, not guilt.
Which Purchases Keep Your Household Fed?
Once the spending is visible, sort each purchase by the job it performs. Ingredients for regular meals, breakfast foods, basic proteins, produce, and items needed for dietary needs belong in the “keeps me fed” group. These purchases deserve protection when the budget tightens, even if their prices are not the lowest. A cheaper substitute that goes unused is still an expensive choice.
Keep preferred foods and convenience items visible, but separate them from the essentials. A favorite coffee, prepared meal, or snack may make the routine easier, especially during a demanding week, yet the cost can crowd out food needed for later meals. Package size adds another constraint: a bulk deal may reduce the unit price while increasing waste for one person. Mark purchases that are necessary, flexible, or occasional. That distinction makes trade-offs clearer without turning every preference into a problem, and it shows how much of the grocery limit must be reserved before anything extra is added.
Leave Room for Plans to Change
That reserved amount should not be treated as money already assigned to specific meals. A late meeting, an unexpected dinner invitation, or a week when cooking feels impossible can change the plan before the groceries are used. Set aside a small flexible portion for those shifts instead of forcing every dollar into a fixed list. For one person, even $10 to $20 can prevent a last-minute purchase from turning into an overspend.
Timing matters as much as the amount. Fresh food bought for a busy week may spoil, while a planned cooking day may disappear. Before shopping, check what is likely to change and choose fewer perishable items when the schedule is uncertain. It may cost slightly more per serving to buy a smaller package, but that can be cheaper than discarding food or ordering takeout. Keep the essential amount protected, then leave the remaining money adjustable. The goal is not to predict the week perfectly; it is to make ordinary changes affordable without rebuilding the entire budget.
Build a Number You Can Use Weekly
With the flexible portion identified, turn the monthly pattern into a weekly number that can guide an actual shopping trip. Add the protected essentials, preferred foods, and planned convenience amount, then divide by four rather than treating every month as exactly four weeks. If the recent average is $360, a starting weekly limit might be about $90, with a small amount held back for the occasional fifth shopping week or a price jump. The calculation matters less than having a number that can be checked before the cart fills.
Use that limit as a range, not a test to pass perfectly. A week with a bulk purchase may run high while the next week uses what is already in the pantry. Track the total at checkout and compare it with the weekly number, including delivery fees and small stops. A $15 overage caused by replacing an empty staple is different from repeated convenience purchases. After a few weeks, adjust the number to match timing, waste, and nutrition rather than forcing every trip into the same pattern.
When Prices Rise, Change the Plan First
When the weekly total rises, changing the shopping plan usually works better than raising the limit immediately. Check which item caused the increase: a staple with a higher price, a seasonal product, or several small convenience purchases. Protect foods that support regular meals and look for adjustments elsewhere, such as buying a smaller amount, choosing a different preparation, or using a pantry item already on hand. A cheaper option only helps if it will actually be eaten.
Timing creates another constraint. If a price jump affects a food bought every week, compare the cost over several trips before making it permanent. One unusually expensive purchase may reflect a stock-up need, not a new baseline. If the higher price continues, move money from flexible categories or reduce waste before expanding the grocery budget. That keeps the weekly number useful while allowing the plan to change with the market.
Review the Budget Without Starting Over
After a few weeks of changing prices and revised shopping plans, review the pattern rather than judging one difficult receipt. Compare what was budgeted with what was spent, then check whether the difference came from higher staple prices, wasted food, extra convenience, or a schedule that changed. A single expensive week may not require action. Repeated overspending in the same category does.
Make one adjustment at a time so the budget remains readable. Raise the amount for a genuine need, reduce a flexible purchase, or change the quantity bought if food is being discarded. Keep the review short—ten minutes with receipts or banking records is enough—and note the reason beside each change. Starting over every month hides progress and makes normal fluctuations feel like failure. A working budget should become more accurate through small corrections, not constant replacement.
A Budget Should Fit Your Real Life
The useful budget is the one that still works when the week is ordinary but not predictable. It protects the foods that support health, leaves room for preferences, and treats convenience as a planned choice rather than a failure. For someone living alone, that may mean accepting a smaller package at a higher unit price when waste is likely, or paying for a prepared meal during an unusually demanding week.
Keep watching the pattern, especially when costs, schedules, or appetite change. A grocery limit should guide decisions before money is spent, not punish decisions made under pressure. If it reflects actual needs and flexible choices, it can change without losing its purpose: keeping food affordable, usable, and suited to real life.