The payday plan that still leaves bills exposed
Payday arrives, the account balance rises, and the month briefly looks manageable. Then rent clears, a subscription renews early, or an automatic transfer lands before the next deposit. Money may be spread across checking, savings, and a bill account, yet the timing still leaves one payment depending on funds that are technically available but sitting elsewhere. The setup feels organized until an ordinary delay exposes the gap.
A payday plan can fail without excessive spending. Transfers may be scheduled for the wrong day, bills may draw from an account with no cushion, or a small account fee may reduce the amount reserved for essentials. One missed movement can turn separate accounts into separate risks. Before adding another rule, it helps to trace what already happens to each dollar after payday.
Start with the money movements you already make
The first useful step is not opening another account or rewriting the budget. It is watching the money move for one pay cycle. Mark the deposit date, every automatic transfer, each bill withdrawal, and the purchases that regularly come from checking. Include small movements: a $15 subscription, a weekly transfer to savings, or a credit card payment that arrives two days earlier than expected.
That record often shows why the plan feels tighter than the income suggests. A bill account may receive enough money for monthly expenses but not early enough to cover a payment scheduled near payday. Savings transfers may leave checking short before groceries or fuel are purchased. A transfer between banks may also take a business day, creating a timing gap even when the total balance is sufficient.
For now, change nothing unless a payment is at immediate risk. Label each movement as essential, flexible, or unclear, then note which account it uses and when it must be funded. The goal is a working map of actual cash flow, not an ideal schedule. That map makes the next decision—what job each account should perform—much less speculative.
Give each account one job to perform
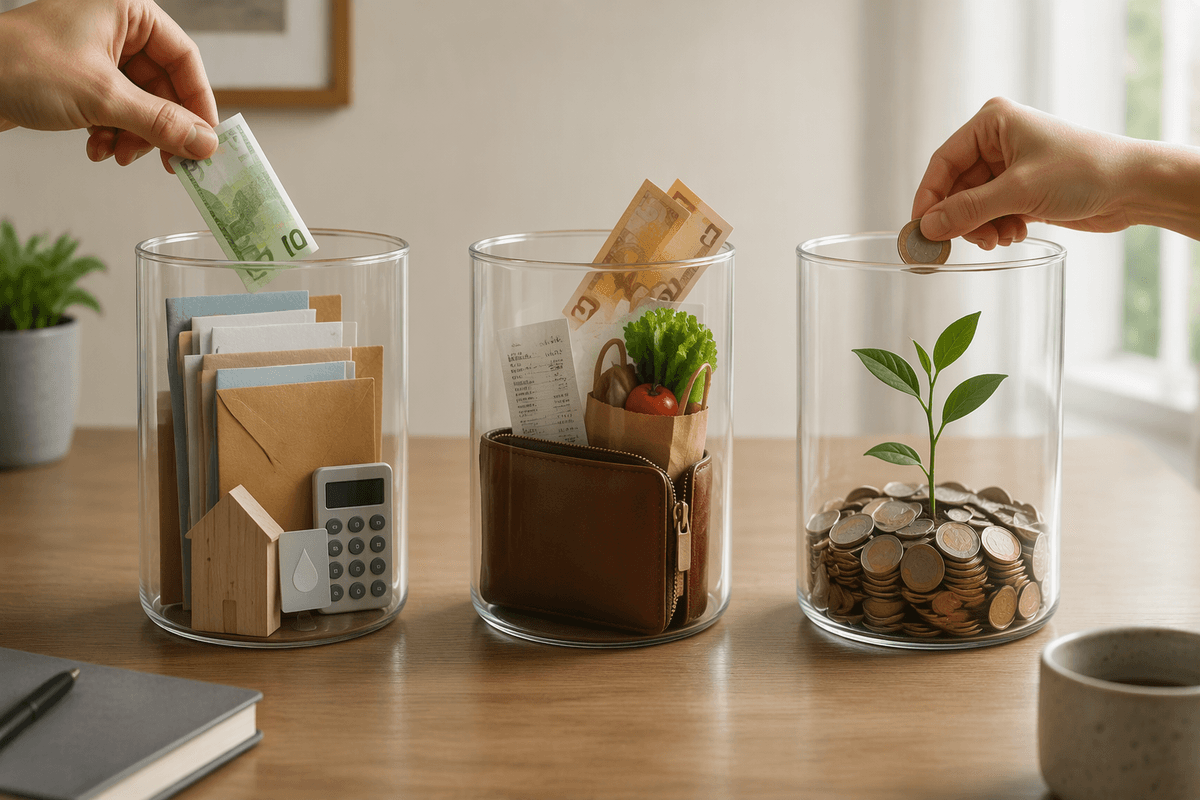
Once the movements are visible, assign each account a single main job. A bills account should hold money for rent, utilities, insurance, debt payments, and other scheduled withdrawals. A spending account can cover groceries, fuel, and ordinary purchases. Savings should hold money that is not expected to return to checking before the next planned review. The labels matter less than the behavior: each balance needs a clear reason for being there.
This separation reduces decisions at the point of purchase. If the spending account is low, that signals a spending limit; it does not automatically mean bill money is available. Likewise, a bill account should not become a temporary parking place for cash needed elsewhere. Keeping extra money there may feel safe, but it can hide how much is genuinely available and leave savings underfunded.
Give the system a practical cushion rather than aiming for exact amounts. A bill account may need an extra $100 to absorb a variable utility charge, while checking may need enough for several days of groceries before the next transfer. Too many accounts create another constraint: more minimum balances, fees, passwords, and transfer dates to track. If an account has no distinct job, combining it with another may improve control rather than weaken it.
When should transfers happen after payday?
With each account assigned a job, the transfer date should follow the cash need rather than the calendar alone. A bills account usually works best when it is funded shortly after payday, while the deposit is still visible and before scheduled withdrawals begin. If payday falls on a Friday but rent clears Monday, moving the money that Friday may be safer than waiting for a standard monthly transfer date.
Leave spending money available for the gap between deposits. Sending every planned dollar away immediately can force a return transfer for groceries, fuel, or an unexpected prescription. That extra movement may take a business day, especially when accounts are at different banks. A practical sequence is to fund essential bills first, keep a known amount in checking for near-term spending, then move savings after those obligations are covered.
Pay attention to weekends, holidays, and irregular pay dates. A transfer scheduled for payday may arrive later than expected, while an automatic payment may still leave on time. The first schedule should include a modest cushion, then be tested against one full pay cycle before becoming permanent.
The balance is not the amount you can spend
After transfers are timed, the next mistake is treating the number on the screen as permission to spend. A checking balance of $900 may include $300 reserved for a bill due next week, $150 for groceries and fuel, and money waiting to move to savings. The visible total is accurate, but it does not show which dollars already have a job.
Use a smaller figure for everyday decisions: the balance minus upcoming bills, pending card payments, scheduled transfers, and a modest cushion. If $900 is showing and those commitments total $600, the practical spending amount may be closer to $300. That estimate should be conservative when payments can post early or a transfer may take a business day. Otherwise, a normal purchase can consume money that was already committed elsewhere.
Pending transactions add another constraint. A debit card purchase may not appear immediately, and a credit card payment can reduce available cash before the account history looks settled. Checking the account on a regular schedule—and recording reserved amounts separately—turns the balance from a misleading headline into a usable cash-flow signal.
Simplify the setup before adding another account
Once reserved money is separated from spendable cash, another account may seem like the obvious fix. Often it only creates another balance to monitor. A second savings account, sub-account, or separate bank can help when it has a clear purpose, but opening one to compensate for an unclear transfer rule usually adds friction instead. There may be minimum-balance requirements, monthly fees, delayed transfers, or another login to check before a bill is paid.
Test the existing setup first. Rename accounts, automate one transfer, or keep a simple note showing reserved amounts before changing the structure. If two accounts perform nearly the same job, combine them or choose one as the primary location for that money. Add an account only when it solves a specific problem—such as protecting emergency savings from routine spending—and confirm the cost and transfer timing. Fewer moving parts make errors easier to spot before the full billing-cycle review.
Review the system after one full billing cycle
After one full billing cycle, compare what was planned with what actually happened. Check whether bills cleared from the intended account, transfers arrived before the money was needed, and the spending balance lasted until payday. Include the small failures: a fee, an early withdrawal, a transfer delay, or a purchase made from the wrong account. These details show whether the system works under ordinary pressure rather than on paper.
Make one adjustment at a time. Increase a cushion, move a transfer date, or remove an account that created more work than control. A workable setup may still need occasional corrections, but it should make upcoming obligations easier to see and reduce emergency transfers. After the review, the goal is not perfect separation; it is fewer surprises at a manageable cost.