The bond looks safe until rates change
A bond can sit quietly in an account for years, sending the same interest payment on schedule. That steadiness often becomes part of its appeal. Then market rates move, and the account statement may show a value that no longer matches the original purchase price. Nothing has changed about the issuer’s promised payments, yet the bond may be worth less if it had to be sold today. The surprise comes from treating “safe” as one thing. Regular income, repayment at maturity, and today’s resale value are separate parts of the decision.
When interest rates rise, newly issued bonds usually offer more attractive payments. An older bond with a lower fixed rate must therefore sell for less to compete. The change may remain only on paper if the bond is held to maturity and the issuer pays as promised. But timing matters: a planned sale, an emergency expense, or a longer wait can turn that quiet price change into a real financial constraint.
Your payment stays fixed; the market price moves
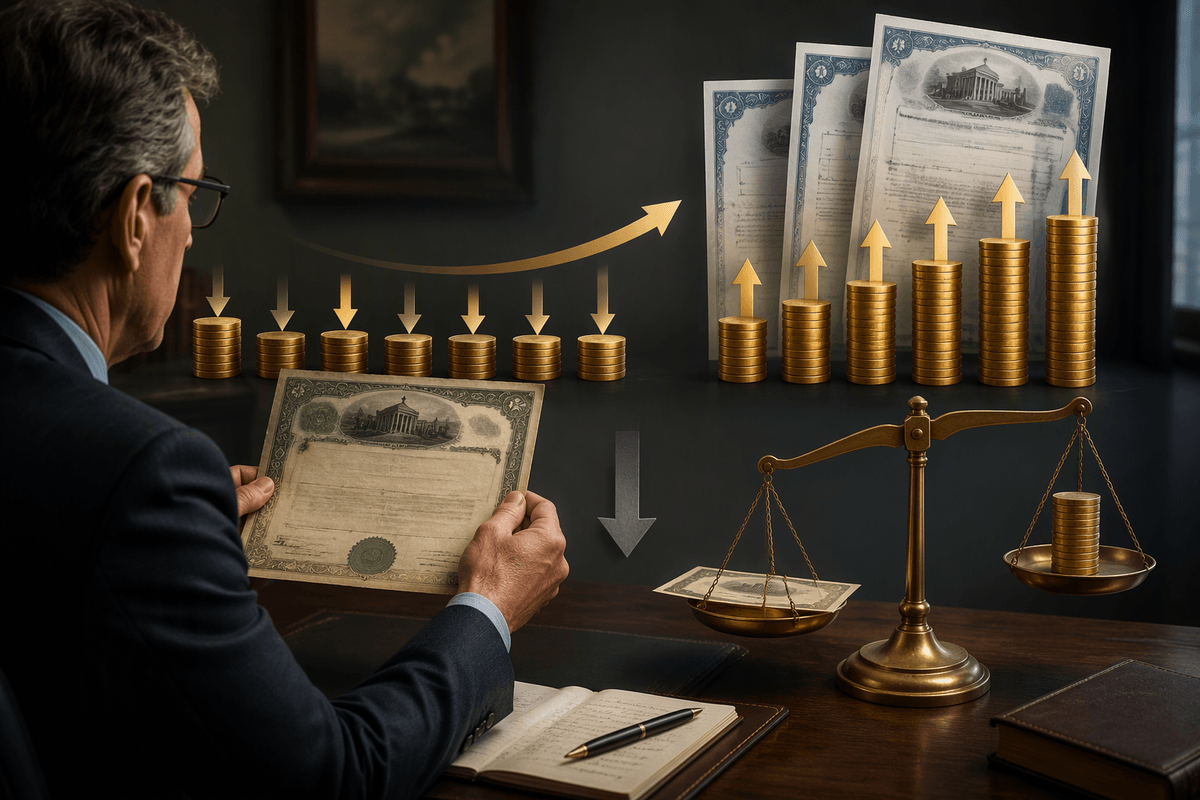
The scheduled payment does not adjust just because market rates do. A bond bought with a 3% coupon generally continues paying that rate according to its terms, whether comparable new bonds now offer 4% or 5%. That fixed income can still be useful, especially for someone relying on predictable cash flow. It does not, however, preserve the bond’s resale value.
Market price reflects what another investor would accept today. If a new bond offers higher interest with similar credit quality, buyers will usually pay less for the older, lower-paying bond. The discount helps bring its overall return closer to current rates, with the exact amount affected by time remaining, credit risk, and payment schedule. A statement showing a $10,000 bond valued at $9,200 does not mean the issuer has reduced the promised payments; it means selling now could return about $800 less before transaction costs and taxes.
That distinction becomes practical when cash is needed before maturity. Holding may preserve the scheduled payments and eventual principal repayment, assuming the issuer remains able to pay. Selling may provide liquidity, but it can lock in the lower market price at an inconvenient moment.
A new bond makes the old one less appealing
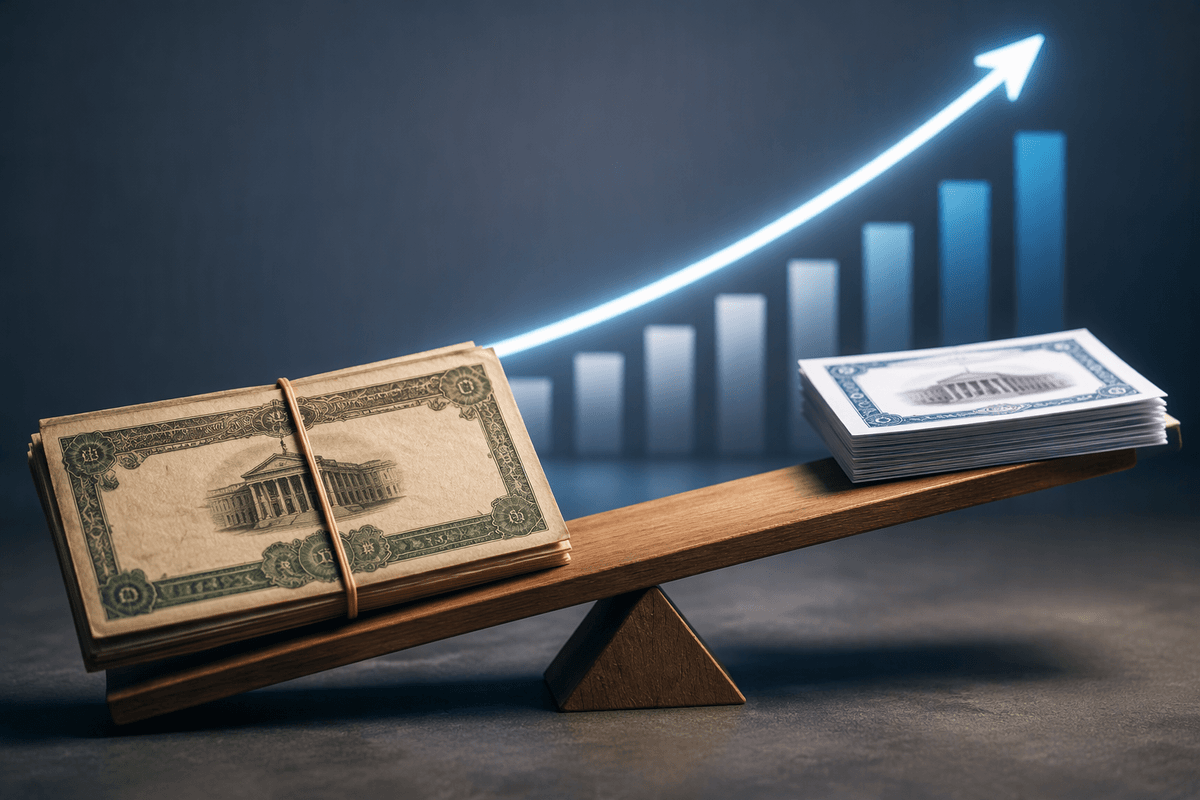
The comparison becomes clearer when two otherwise similar bonds sit side by side. Suppose an older bond pays $300 a year on a $10,000 investment, while a newly issued bond with similar credit quality pays $400. The older bond has not broken its promise, but its income now looks thin beside the available alternative. A buyer considering both would likely demand a lower price for the older bond, enough to make its lower payments more competitive over the remaining term.
That adjustment is shaped by more than the coupon rate. The buyer also considers how long the bond will continue paying less than current rates and whether the issuer carries additional risk. A bond with five years left may need only a moderate discount; one with decades remaining may require a much larger one. For an investor who already owns the older bond, the uncomfortable choice is not simply “safe or unsafe.” It is whether the existing income is worth keeping when newer bonds offer more, and whether switching requires accepting a loss, paying transaction costs, or giving up a payment schedule that still fits near-term expenses.
Long maturities magnify the uncomfortable difference
The longer a bond has to keep paying below current market rates, the more pressure falls on its price. A bond maturing next year may be only modestly inconvenient if it pays 3% while new bonds pay 4%; the buyer will soon receive the principal back and can reinvest it. A bond maturing in 20 years offers far less flexibility. Its lower payments remain locked in for much longer, so a larger discount may be needed to attract a buyer.
That time difference also makes rate changes harder to absorb. If rates rise again, a long-term bond can lose additional market value because its fixed payments look even less competitive. The decline does not change the scheduled income or the principal due at maturity, but it can matter greatly for someone who may need the money sooner. Selling after a major rate increase could mean accepting a sizable loss, while holding requires tolerating years of below-market income. The maturity date therefore becomes more than a promise of repayment; it sets how long the investor may be tied to an outdated rate.
Selling today turns a paper loss real
The loss becomes financial only when the bond is sold below its purchase price. Until then, the lower value is an account statement figure, not necessarily a permanent reduction in the payments or principal scheduled by the issuer. That distinction can make holding seem sensible, but it does not remove the cost of waiting. Money remains tied up in a bond that may be earning less than newly available alternatives.
Selling can still be the better choice when cash is needed, the bond no longer fits the portfolio, or a higher expected income matters more than recovering the original amount. The trade-off is immediate: a bond bought for $10,000 and now worth $9,200 produces a roughly $800 loss before fees and taxes if sold. Reinvesting that $9,200 at higher rates may improve future income, but it cannot erase the amount already lost. A rushed sale during an emergency leaves little room to compare those outcomes, which is why liquidity needs matter before rates move, not after.
Holding can work, but only under conditions
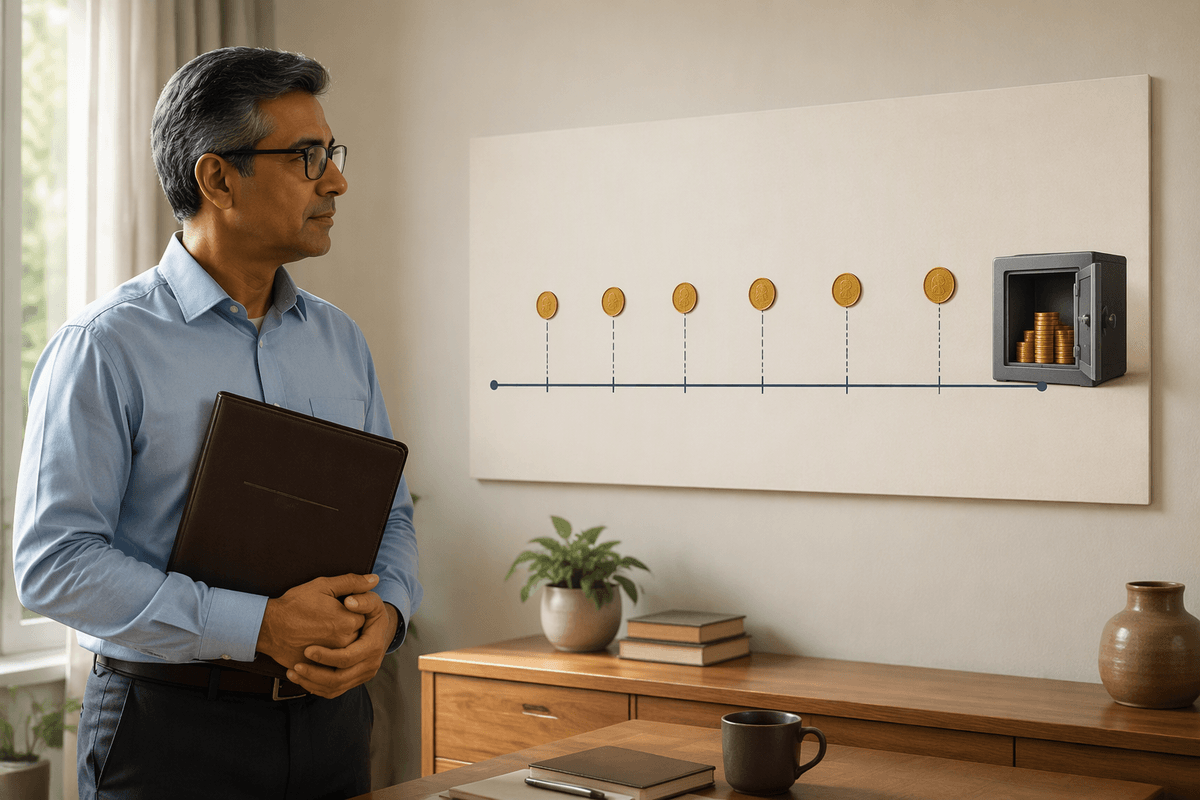
Holding remains reasonable when the bond’s maturity matches the date the money is needed and the issuer is still expected to pay. In that case, the market discount may be uncomfortable without changing the planned outcome: scheduled interest continues, and principal is returned at maturity. The investor accepts lower income than new bonds offer in exchange for avoiding a sale at today’s reduced price.
That choice becomes weaker when the maturity is far away, expenses may arrive sooner, or the bond’s credit quality has deteriorated. Waiting is not free; each year may leave money earning less than comparable alternatives, and a future cash need could force a sale under worse conditions. A hold decision therefore depends on more than whether the loss is labeled “unrealized.” It works best when cash-flow needs are covered elsewhere, the issuer remains dependable, and the investor can tolerate lower payments until maturity.
Use maturity, income needs, and alternatives together
The decision becomes clearer when the bond is viewed alongside the date the money may be needed and the income available elsewhere. A bond maturing soon may be worth holding despite a lower rate, especially if its payments cover planned expenses. A long-term bond deserves more scrutiny when newer investments offer better income and the funds may be needed before maturity.
Alternatives also carry constraints: selling may create a loss, fees, or taxes, while switching may improve future income without restoring the original principal. The practical question is therefore narrower than whether rates rose. It is whether the bond’s remaining term and cash flow still fit the plan better than the choices available today.