The Card That Looked Better on Paper
The card looked like an easy upgrade. Its headline rate was higher, the welcome offer was larger, and the rewards table seemed designed for frequent spending. Months later, the statement told a less flattering story: several purchases earned little or nothing, the annual fee had arrived, and the points were worth less than expected at checkout. The card had not changed; the assumptions behind the comparison had.
That gap matters when deciding whether to keep a card or switch. A rate that looks impressive in an advertisement can lose its advantage through spending limits, excluded categories, redemption rules, or a fee that arrives before the rewards accumulate. The useful comparison starts with actual purchase patterns, not the most attractive number on the application page.
Start With Where Your Money Already Goes
The first useful step is less glamorous than comparing reward tables: pull several recent statements and sort the spending into broad categories. Groceries, dining, fuel, travel, recurring bills, and everything else usually reveal a different picture from the sample budget used in a card advertisement. A category that earns 5% may account for only a small share of monthly spending, while ordinary purchases earning 1% or 1.5% make up most of the balance.
Use a long enough period to catch irregular costs, but not so long that old habits distort the decision. Three to six months is often enough to expose patterns, including purchases that do not qualify because of merchant coding, payment method, or a rewards cap. The exercise also catches timing issues: a card may offer an elevated rate only for a quarterly category, while spending shifts before the quarter ends. That matters more than a theoretical maximum that requires constant monitoring. Once the actual mix is visible, the comparison becomes narrower—and the next question is which card pays more on those specific purchases.
Which Card Pays More for Those Purchases?
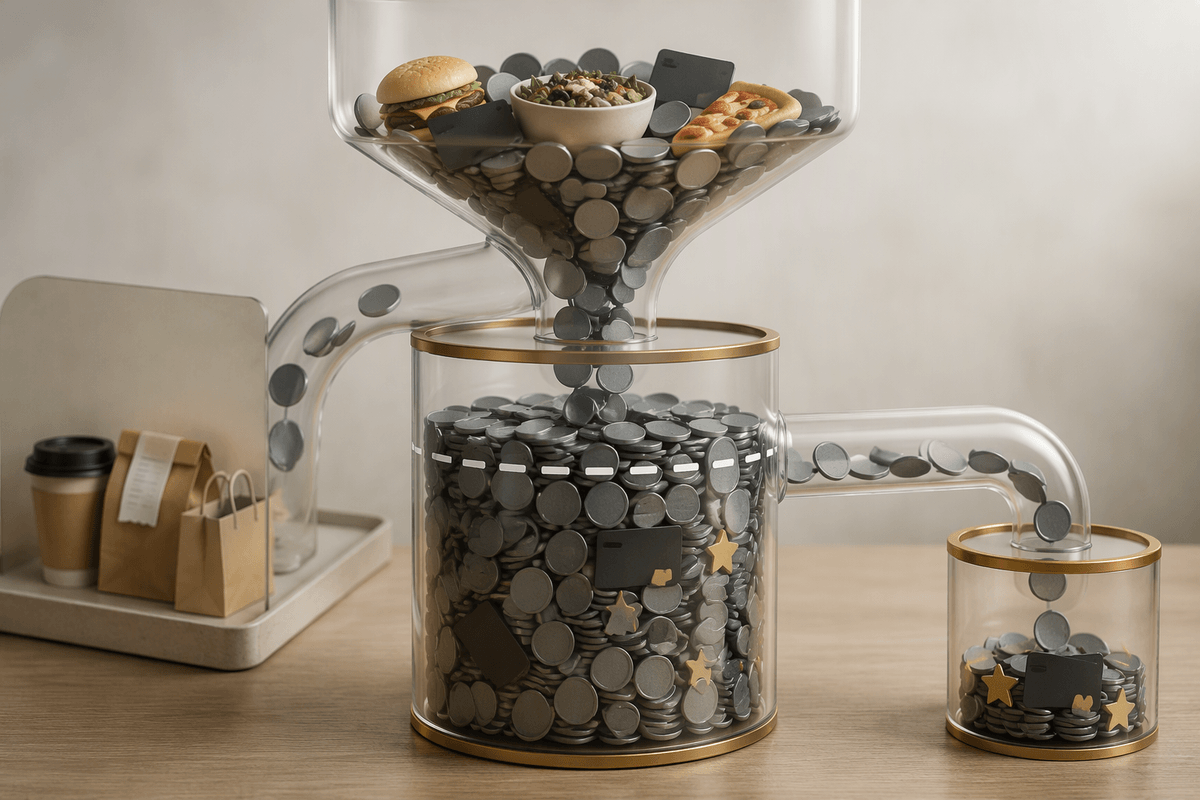
With the spending mix in view, compare the rewards each card would produce on the same purchases rather than comparing the highest advertised rate. A card offering 4% on dining may look stronger than one offering 2% everywhere, but the broader card can win if dining represents only a small portion of the budget. Apply each earning rate to actual monthly or annual amounts, then separate points from cash back so the comparison does not treat them as equal automatically.
Redemption value can change the result. Ten thousand points may cover $100 of statement credit but produce $140 when transferred for a specific trip—or far less if the available options are limited. That higher value may also require planning, blackout-date flexibility, or enough points to reach a redemption threshold. Caps create another constraint: a 5% rate on the first $1,500 each quarter is not a 5% return on all spending in that category. After the cap, the rate may fall sharply, and an excluded purchase can earn nothing. A simple estimate should therefore show both the expected reward and the assumptions required to achieve it. Only then is it clear whether the apparent lead survives ordinary spending.
The Annual Fee Can Reverse the Ranking
Once the rewards estimate is on the page, subtract the annual fee before treating one card as the winner. A card that earns $280 in rewards but charges $95 may deliver less usable value than a no-fee card earning $210. The difference becomes even smaller when a fee posts before spending has built enough rewards to offset it, or when the cardholder keeps the account open during a low-spending year.
Credits can make the calculation look better, but only if they match expenses that would happen anyway. A $100 travel credit has little practical value if using it requires booking through a restricted portal, paying higher prices, or taking an unnecessary trip. The same caution applies to monthly dining or subscription credits that expire when unused. Compare the net value under two views: the full advertised value and the amount realistically captured without changing normal behavior. A modest reward rate may rank higher once the fee, unused credits, and redemption friction are removed. That revised ranking sets up the harder question: whether the extra earnings are actually worth the effort and restrictions attached to them.
Earning More Does Not Guarantee Better Value
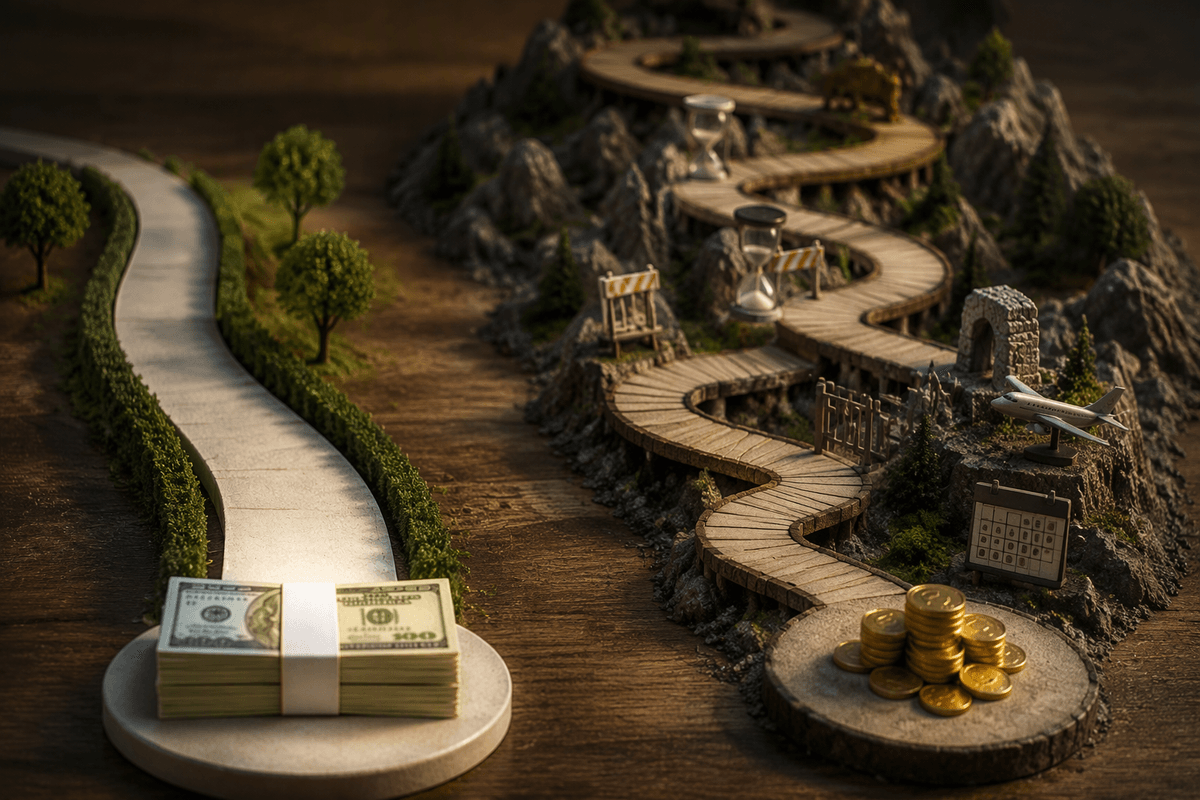
The higher earning rate can still produce weaker value when capturing it changes how spending is handled. A card may require rotating categories, specific portals, minimum redemption amounts, or transfers to partners before the rewards reach their best value. Missing one activation deadline or using points for a low-value redemption can erase much of the advertised advantage. Even ordinary friction has a cost when tracking categories becomes another monthly task.
There is also a difference between rewards earned and rewards used. Cash back is usually straightforward, while travel points may deliver more only when dates, routes, and availability line up. A balance that sits unused for months is not worth its headline value, especially if terms can change or an account is closed before redemption. Estimate the result using the redemption method most likely to be used, then discount any value that depends on extra purchases, forced travel, or complicated timing. The card earning the most points is not necessarily producing the most usable return. Once that distinction is clear, the comparison needs to account for what happens when spending patterns change.
Test the Rewards Against Realistic Changes
A reward estimate should survive more than one version of the budget. Recalculate it after reducing the highest-earning category, removing a planned trip, or shifting several purchases to cash or another card. A program that wins only when every category is fully used may not hold its lead during a job change, move, or tighter month. Spending caps and minimum redemption thresholds can make a small decline more expensive than the headline rates suggest.
Run the comparison with a likely low-spending year as well as the recent average. Include the possibility that a quarterly bonus is missed or a credit goes unused. If the result changes sharply after one ordinary adjustment, the advantage is fragile. That does not automatically rule out the card, but it makes the annual fee and management effort harder to justify.
Choose the Card You Can Keep Using
The final choice should hold up after the attention fades. If a card requires constant category tracking, portal bookings, or spending that would not happen otherwise, its theoretical return may not survive ordinary months. A simpler card can be the better keeper when it earns reliably, has a manageable fee, and fits the way purchases are already made. Switching also has costs: a new application may affect credit, unused points may be stranded, and closing an older account can reduce available credit.
Before applying or canceling, compare the net reward under normal spending and a lower-spending year, then ask whether the redemption process will actually be used. The strongest card is not always the one with the highest rate. It is the one whose value remains visible after fees, limits, missed bonuses, and changing circumstances are taken away.