When Equal Splits Start Feeling Unfair
At first, splitting household costs in half can feel refreshingly simple. Rent is divided, the utility bill is settled, and neither partner has to explain every purchase. The arrangement often works while incomes and spending patterns are similar. Pressure appears when one person earns less, covers more unpaid household work, or spends far less on shared comforts. A $1,200 rent payment may be equal on paper but difficult in practice when one partner has only $2,000 left after taxes and the other has $4,000. Resentment rarely begins with one dramatic bill; it grows through repeated moments when “equal” stops feeling manageable.
That tension is a signal to examine the system, not assign blame. Before changing percentages or opening accounts, separate costs both partners benefit from from spending that belongs to one person alone.
First, Separate Shared Costs From Personal Spending
Start with a list of bills and mark each one by how clearly it serves the household. Rent, basic utilities, internet, shared groceries, and agreed household supplies usually belong in the common pool. A prescription, hobby purchase, personal loan, clothing, or meal ordered for one person usually does not. The gray areas need a conversation: streaming services, commuting costs, takeout, pet expenses, and upgrades to the home can look shared while benefiting one partner more.
Keep the first version practical rather than perfectly precise. Separate recurring essentials from optional extras, then agree on a simple rule for anything uncertain. Without that step, a fifty-fifty split can quietly subsidize one partner’s habits, while detailed tracking can consume more time than the savings justify. A shared spreadsheet or monthly list is often enough. Once the common total is visible, the next question becomes manageable: should both partners contribute the same amount, or should the burden reflect what each can reasonably afford?
Does Fifty-Fifty Still Work For Both Partners?
With the shared total in view, test the fifty-fifty method against real monthly cash flow rather than treating it as automatically fair. If household costs reach $2,400, each partner would contribute $1,200. That may be reasonable when both take home similar amounts and retain comparable room for savings, debt payments, and personal needs. It becomes harder when one partner earns $3,000 a month and the other earns $5,000. The lower earner may still pay half the bills, but have far less left afterward for emergencies or ordinary spending.
Equal contributions can still work when both partners genuinely prefer the simplicity and neither is quietly cutting back to keep up. The warning signs are practical: missed payments, growing credit-card balances, skipped savings, or one person needing permission for small purchases. Consider the effect of irregular income as well. A bonus, freelance payment, reduced work schedule, or unpaid leave can make a fixed fifty-fifty amount unworkable for several months. Before changing the arrangement, compare what each person has left after shared costs, not just what each person puts in. If the remaining amounts are sharply different, an income-based contribution may reduce pressure without turning every purchase into a negotiation.
Income-Based Contributions Change The Pressure
An income-based arrangement starts by treating the shared total as a joint responsibility while recognizing that equal dollars do not create equal pressure. If one partner brings home $3,000 and the other $5,000, a 37.5% and 62.5% split would match their take-home income. On $2,400 of household costs, that means contributions of $900 and $1,500. The lower earner keeps more room for debt payments, savings, or unexpected costs, while the higher earner contributes more without having to cover every personal expense.
The percentage should be based on a number both partners trust. Take-home pay is usually more practical than salary, particularly when taxes, health insurance, or retirement deductions differ. Discuss whether bonuses, commissions, freelance work, or unpaid leave should change contributions immediately or only during a scheduled review. A temporary income drop can make a rigid formula stressful, while constantly recalculating after every paycheck creates its own friction. Also account for unpaid childcare, home maintenance, or reduced work hours if those efforts support the household. The goal is not mathematical perfection. It is a contribution rule that leaves both partners with reasonable personal flexibility and does not turn income differences into a permanent source of obligation.
Usage-Based Rules Help, Until Tracking Takes Over
Income is not the only source of imbalance. Usage-based rules can make sense when one partner works from home, drives more, cooks most meals, or prefers a higher level of heating and air conditioning. A person who spends most weekdays at home may reasonably cover a larger share of the electric bill, while the partner who rarely drives may contribute less toward fuel or parking. These adjustments can feel fair when the difference is obvious and the dollar amount is meaningful.
The difficulty starts when every bill requires investigation. Measuring showers, counting grocery items, or dividing each restaurant order can turn ordinary household life into bookkeeping. The time cost may exceed the savings, and small differences can create arguments out of proportion to the money involved. Use usage-based rules only for clear, recurring gaps, then keep the method broad: an agreed extra percentage or monthly amount is usually better than tracking every unit. If the arrangement needs constant evidence to feel fair, a simpler income-based split or shared account may create less pressure.
A Joint Account May Simplify The Monthly Routine
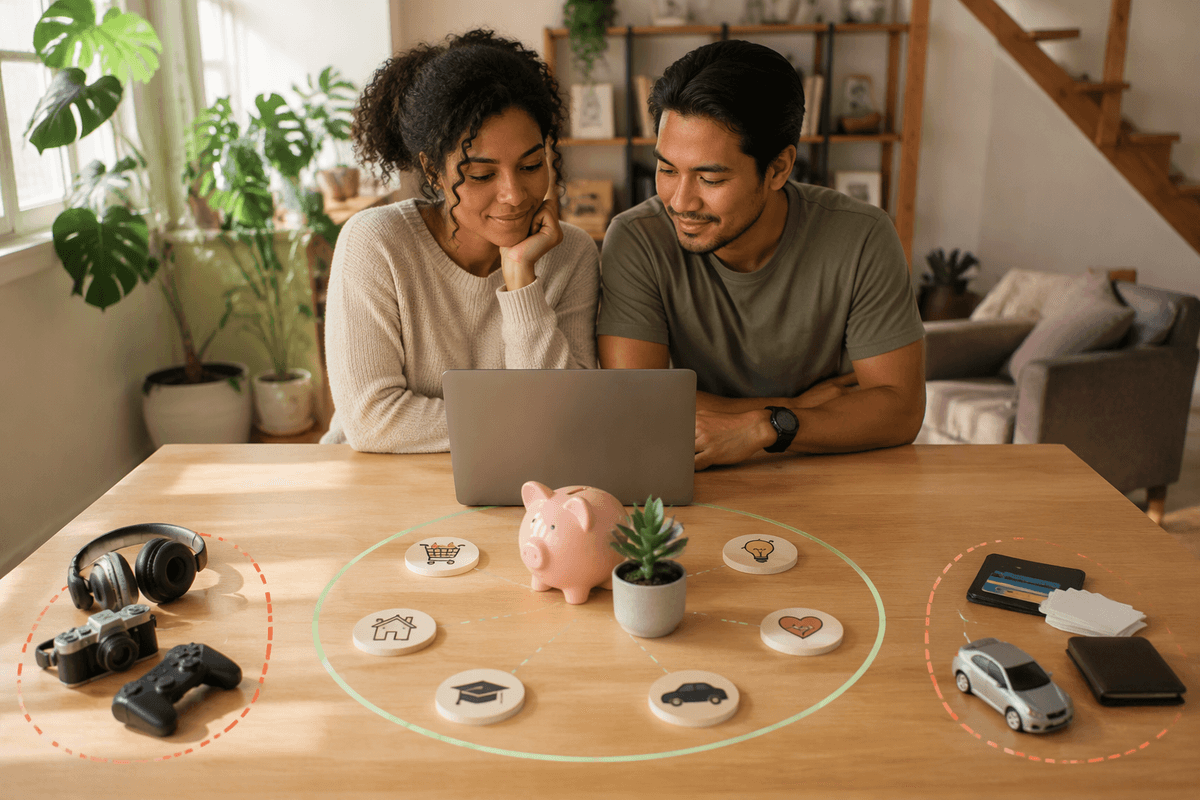
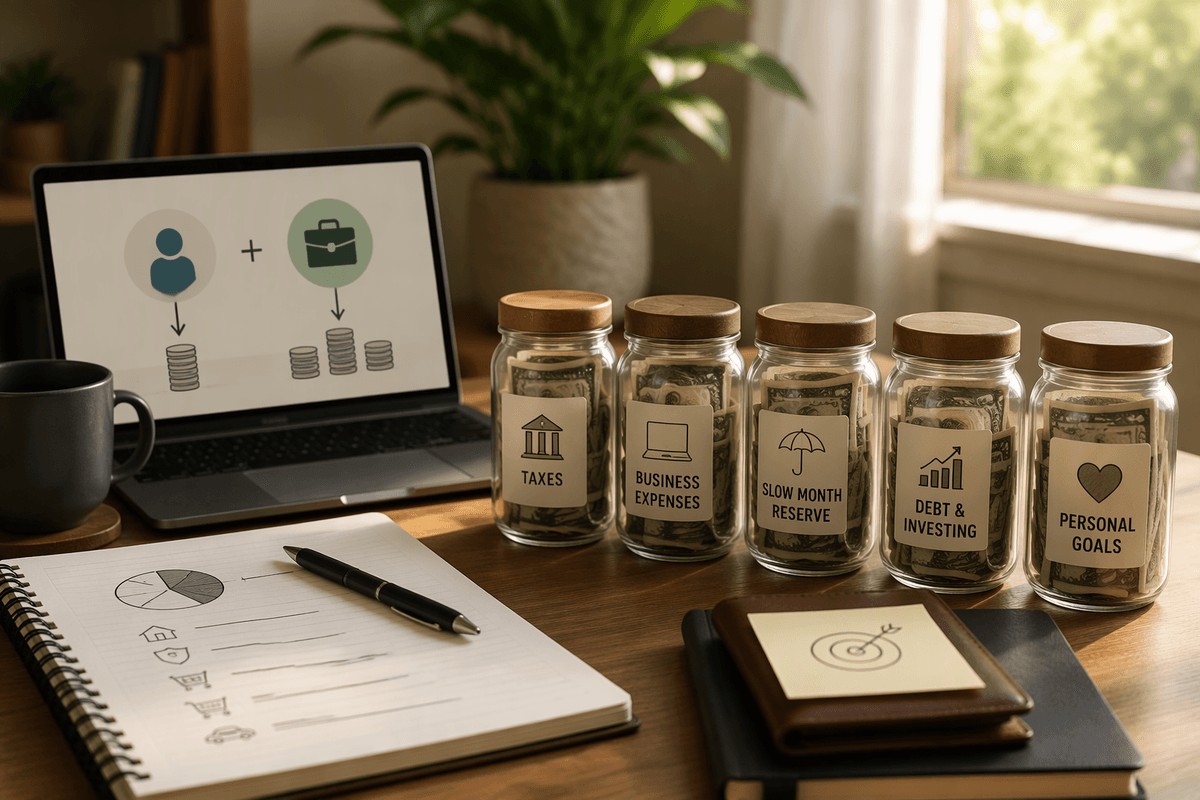
When usage rules start requiring constant calculation, a joint account can move the routine back toward the household itself. Each partner transfers an agreed amount after payday, based on an equal split, income percentage, or another rule already discussed. Rent, utilities, groceries, and planned household bills are then paid from that account instead of being reimbursed one purchase at a time. The practical benefit is timing: neither person has to wait for repayment or wonder whether a large bill will disrupt the rest of the month.
The account still needs boundaries. Keep personal spending and existing debts outside it, decide whether a small buffer is required, and agree on what purchases need both partners’ approval. Automatic transfers can fail when income changes, so review the balance before overdrafts or credit-card use become the backup plan. A joint account does not settle disagreements about fairness; it simply makes the chosen arrangement easier to follow. If contributions are unclear or one partner feels watched, separate accounts with scheduled transfers may be more comfortable. The monthly system should reduce bookkeeping, not create a new source of suspicion.
Review The Arrangement Before Resentment Returns
Once the monthly routine is running, put a review date on the calendar before either partner feels trapped by it. Every three or six months, compare actual bills with the original estimate, check whether contributions still match income, and ask whether either person is delaying savings or relying on credit to keep up. A raise, job change, move, new debt, or shift in household work can change what felt reasonable earlier. Keep the review focused on the rule, not on who spent more last month. Small adjustments made while the arrangement is still working are easier than rebuilding trust after resentment has become part of every bill.