The Three-Month Break Looks Affordable—Until Income Stops
At first glance, three months away from work can look like a simple savings exercise: add up rent, food, and bills, then multiply the total by three. The estimate often feels manageable while the salary is still arriving. That confidence changes once the final paycheck clears. Health coverage may cost more, debt payments continue, and ordinary surprises—car repairs, medical bills, a family emergency—still appear on schedule. A return to work may also take longer than expected, leaving savings to cover a fourth month or more. The real decision is not whether three months can be funded on paper, but whether the plan can absorb the costs that refuse to pause.
Start With the Cash You Cannot Avoid
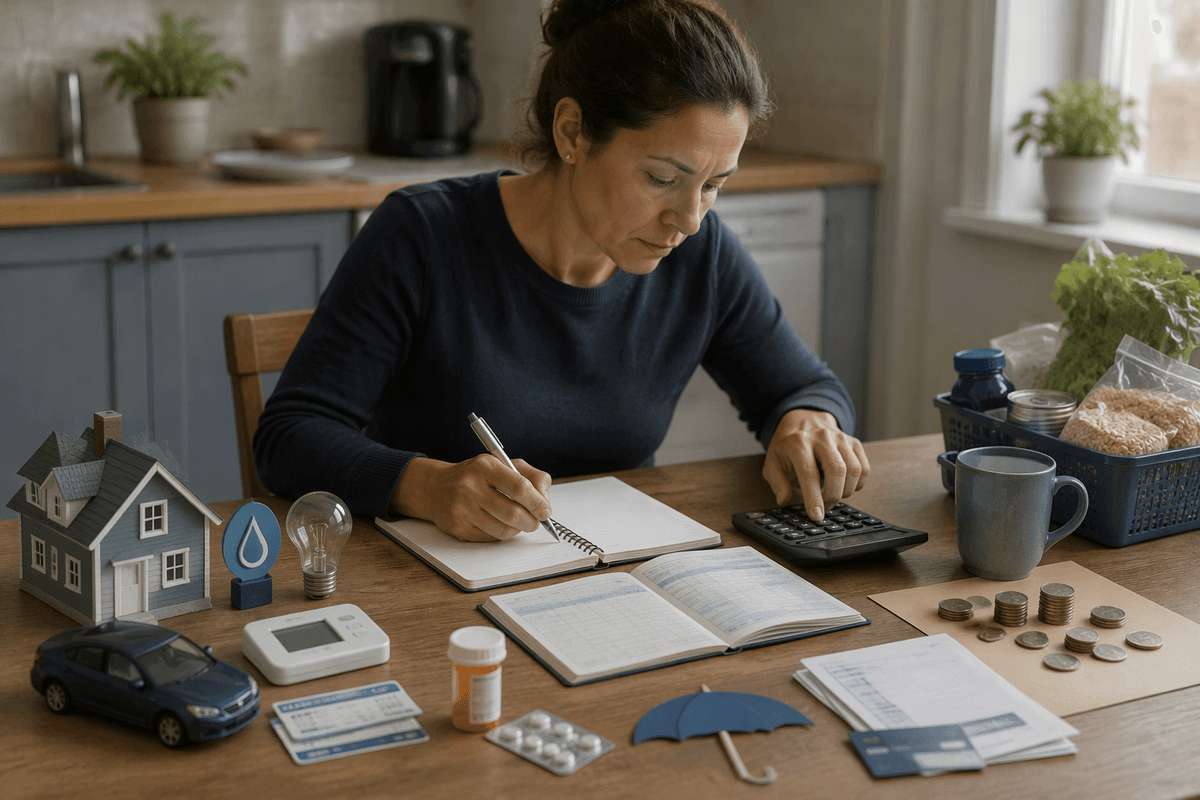
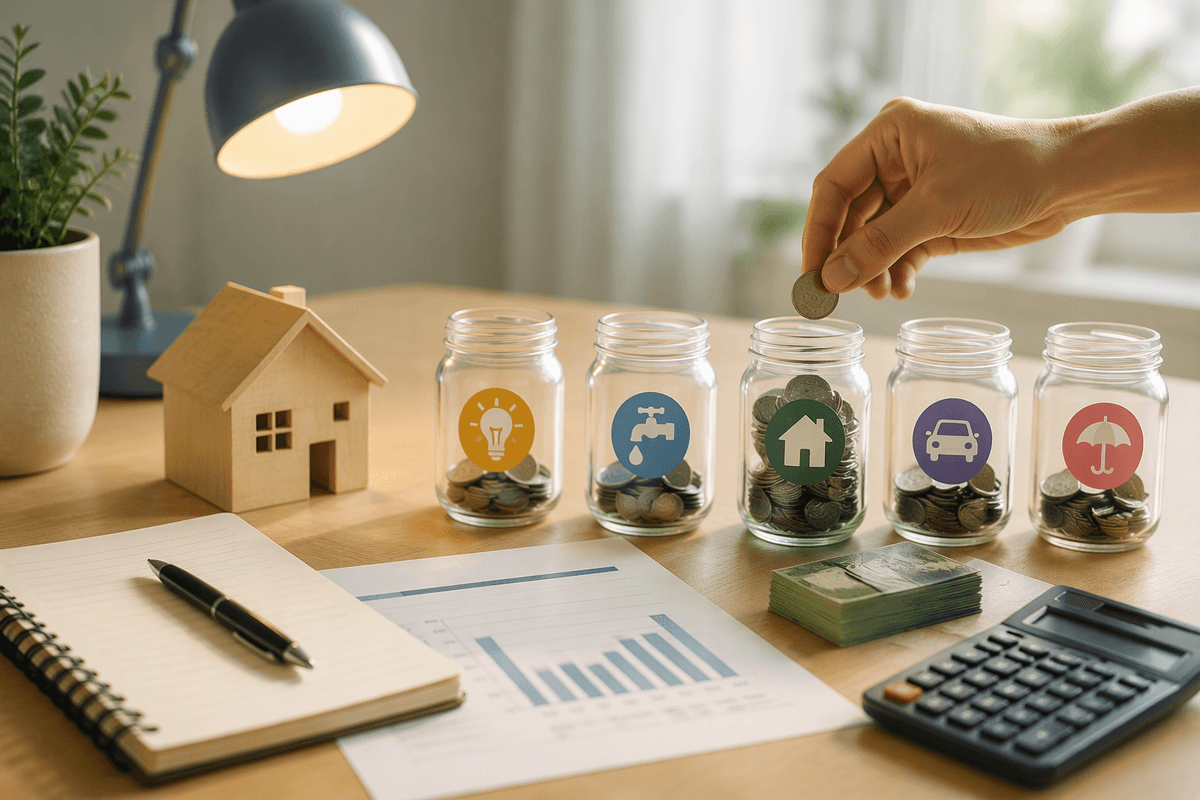
The first figure to pin down is not the amount that feels comfortable, but the cash that must leave the account every month. Rent or mortgage, utilities, insurance, minimum debt payments, transportation, prescriptions, and basic groceries belong in this group. They do not become optional because work has paused. Include annual bills by converting them into monthly amounts; a car registration payment due during the break can disrupt an otherwise tidy budget.
Then add costs created by leaving employment. Health insurance may shift from a payroll deduction to a much larger direct payment, while retirement contributions, employer-paid life insurance, or other benefits may disappear. Check the timing as well as the amount: a final paycheck may arrive before the break, but a benefit premium or loan payment could be withdrawn afterward. Once these unavoidable costs are totaled, multiply them by three and add at least one extra month if the return date is uncertain. That number is the floor, not the full target. It leaves no room for a broken water heater, a family obligation, or a job search that takes longer than planned.
Your Regular Paycheck Hides Several Extra Costs
The monthly total can still look too clean if it only captures bills sent to the household. A regular paycheck often covers costs indirectly: payroll taxes, health premiums, commuting, work clothes, lunches, parking, professional dues, and automatic retirement contributions. Some of these expenses may fall during a break, but others change rather than disappear. Cooking at home can reduce weekday spending, while replacing lost employer benefits can add hundreds of dollars to the monthly draw.
Review the last three months of bank and card statements before treating any category as settled. Look for expenses that arrive irregularly, such as prescriptions, subscriptions renewed annually, dental care, school costs, or support for relatives. Timing creates another trap: a bill charged after the final paycheck still belongs to the break, even if it reflects an earlier purchase. Separating costs that stop, costs that shrink, and costs that continue gives a more useful estimate than applying a blanket reduction. The savings target may rise, but it also becomes easier to see which changes are realistic and which would create new stress.
Choose What the Break Is Allowed to Cost
Once the hidden costs are visible, the decision becomes less about reaching one perfect savings number and more about choosing the level of strain the break can carry. A lean plan might cover only fixed bills and basic food, while a steadier plan preserves room for travel, hobbies, gifts, or occasional meals out. Neither is automatically right. The cheaper version becomes risky if it depends on constant discipline or leaves no money for a routine surprise.
Set a firm spending limit for the break, then separate planned flexibility from emergency cash. For example, a monthly allowance can cover ordinary extras, while a separate reserve remains untouched unless the car needs repairs or the return to work slips. Cutting the allowance later is easier than rebuilding an emergency fund after it has been spent. Debt deserves its own trade-off: paying only minimums may protect cash now but increase interest, while making large extra payments can leave too little liquidity. The workable target is the amount that funds the break without turning every unexpected expense into a reason to return early—or borrow.
Build Protection for the Month That Never Ends
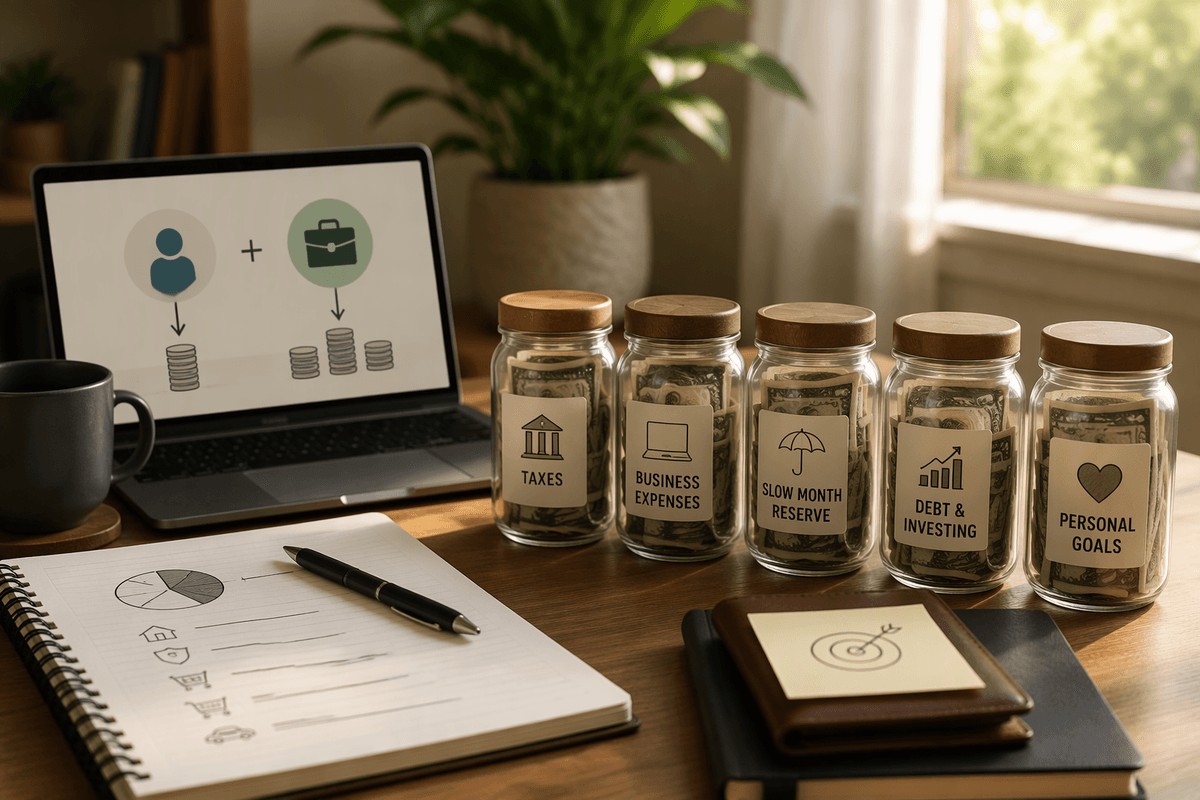
The reserve needs to protect against more than an expensive week. Set aside a separate amount for the month after the planned return date, when savings may be low but income has not yet restarted. A job offer can take time to accept, a start date can move, or the first paycheck can arrive weeks after work begins. Covering one additional month of unavoidable costs is a useful minimum; two months may be more appropriate when the industry is slow, the role is specialized, or health coverage depends on finding a new employer.
Keep this money easy to reach and difficult to spend casually. A separate savings account is often more practical than investments that could fall in value just when the cash is needed. Label the reserve for its actual purpose: delayed income, medical costs, urgent travel, or a major repair. If using it would force new debt, the break is not fully funded yet. That may mean postponing the trip, shortening the leave, or keeping more cash instead of paying down a low-rate loan. The goal is not to predict every surprise, but to prevent one ordinary setback from ending the break on unfavorable terms.
Test the Plan Before You Hand In Notice
Before giving notice, run the plan as if the paycheck has already stopped. Move the planned monthly amount into a separate account on each payday and live on what remains. Continue this test for at least two or three months, including any benefit premiums, debt payments, and annual bills that fall due. The balance should rise by the amount intended for the break, not disappear through small exceptions. If the test requires credit cards, transfers from investments, or repeated cuts to essentials, the budget is describing an intention rather than a workable plan.
Use the trial to expose timing problems as well. Check whether the final paycheck, insurance change, and first post-break income arrive when expected, then model a fourth month without earnings. A modest repair or medical bill should not immediately consume the return reserve. Adjust the break length, spending limit, or cash target while employment income is still available. Once the trial survives ordinary friction without borrowing, handing in notice becomes a measured decision rather than a forecast based on an unusually quiet month.
Leave With a Clear Stop-Signal and Return Plan
Before the break begins, write down the conditions that would end it early. That might be a reserve falling below a set balance, a debt payment becoming difficult, health coverage changing unexpectedly, or the return fund being needed for an emergency. A stop-signal prevents a difficult month from becoming a hidden financial slide. Review the numbers weekly, not just when the account feels low.
Set a return date, but treat it as a decision point rather than a promise. Begin contacting employers, updating applications, or confirming a return-to-work arrangement before savings reach the final reserve month. If the break runs longer than planned, the response should already be clear: reduce spending, resume work, extend only with confirmed cash, or use the remaining reserve to protect essentials. The break is financially ready when leaving and returning are both funded.