The Budget Looks Fine Until the Bills Arrive
At the start of the month, the numbers can look reassuring. Rent is covered, the usual transfers are scheduled, and a little money appears available for groceries, savings, or repairs. Then the electricity bill arrives higher than expected, the water charge posts late, or an annual fee lands in the same week as everything else. Nothing was necessarily spent carelessly; the plan simply treated changing costs as if they were fixed.
That gap makes a budget feel unreliable. Fixed costs stay broadly predictable, while variable bills move with weather, usage, timing, or household needs. Irregular costs create a separate problem because they may be absent for months before demanding cash at once. Until those differences are visible, the amount that looks safe to spend is often money already promised elsewhere.
Start With What Actually Changes
The first useful change is to stop grouping every bill under “monthly expenses.” Rent, insurance, and a regular debt payment are fixed enough to place in the calendar at their full amount. Electricity, fuel, groceries, and mobile data are variable: they arrive regularly, but the amount responds to weather, usage, prices, or household choices. A property tax bill, car registration, school charge, or annual subscription is irregular because the timing matters as much as the total.
That distinction changes how cash should be held. Fixed costs need first claim on each paycheck. Variable costs need a working range, based on several recent bills rather than the cheapest month. Irregular costs need a separate monthly reservation, even when no payment is due yet. A $600 insurance payment due twice a year is not really a surprise; it is a $100 monthly obligation that has been waiting. The practical constraint is incomplete information: a few months may miss a hot summer, a rate increase, or a yearly fee. Mark each expense by behavior, then review at least twelve months of statements where possible. The goal is not perfect prediction. It is preventing a quiet month from making an unstable expense look harmless.
Averages Can Hide the Month That Breaks
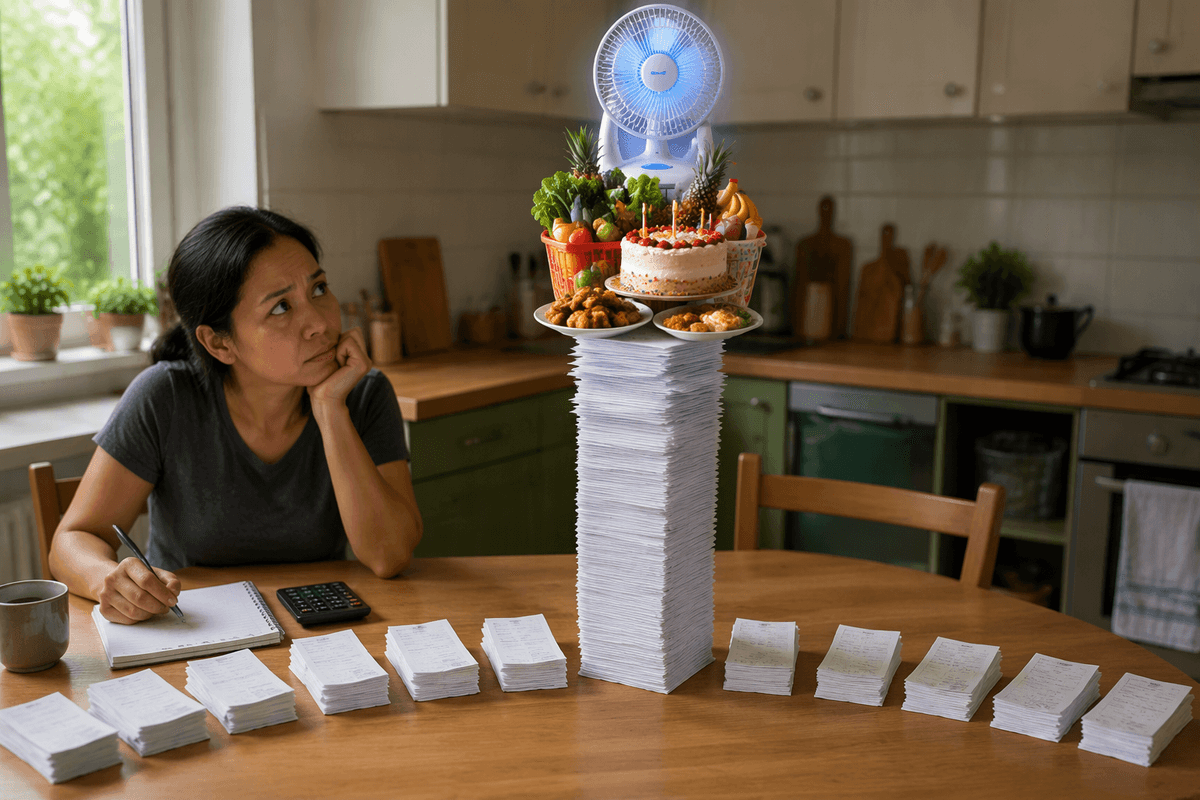
Once expenses are separated by behavior, the next temptation is to average them. That helps describe a year, but it can mislead a month-to-month plan. Electricity might average $145 across twelve bills while reaching $240 during a heat wave. Groceries may average $700, yet a month with a birthday, visitors, or higher prices can push the total well beyond that figure. The average is not wrong; it is simply too smooth for a cash account that must survive the highest bills when they arrive.
Look at the spread as well as the midpoint. For each variable expense, note the lowest, typical, and highest recent amount, then ask whether the household could cover the high month without using a credit card or skipping savings. Timing adds another constraint: two “normal” bills may arrive together after a delayed statement, creating a shortfall even when the annual total seems manageable. A budget built only on averages leaves no margin for that collision. Use the average to estimate the long-run cost, but use the higher observed months to judge the reserve required.
Choose a Safe Number Before a Comfortable One
That higher month gives the budget a more useful starting point: decide what must remain available before deciding what feels comfortable to spend. If electricity has reached $240, groceries have reached $820, and several smaller bills tend to rise together, the plan should first protect against that combination. A safe number is based on observed pressure, not on the amount left after an average month. It may feel unnecessarily cautious when bills come in low, but that extra cash is buying time until the pattern becomes clearer.
Set a working reserve for variable essentials, then treat the balance above it as available only after upcoming due dates are covered. The reserve does not need to match every worst-case bill forever. A sudden rate change, unusually cold month, or delayed payment can make a perfect maximum too expensive to maintain. Begin with the highest recent amount, or a rounded figure slightly below it if cash is tight, and test whether the account can absorb one difficult month without borrowing. The constraint is competing priorities: holding more cash reduces immediate spending or saving, but holding too little turns a normal fluctuation into a financial emergency. Comfort can be added later, after several billing cycles show that the lower reserve is genuinely holding.
Build Separate Reserves for Uneven Costs
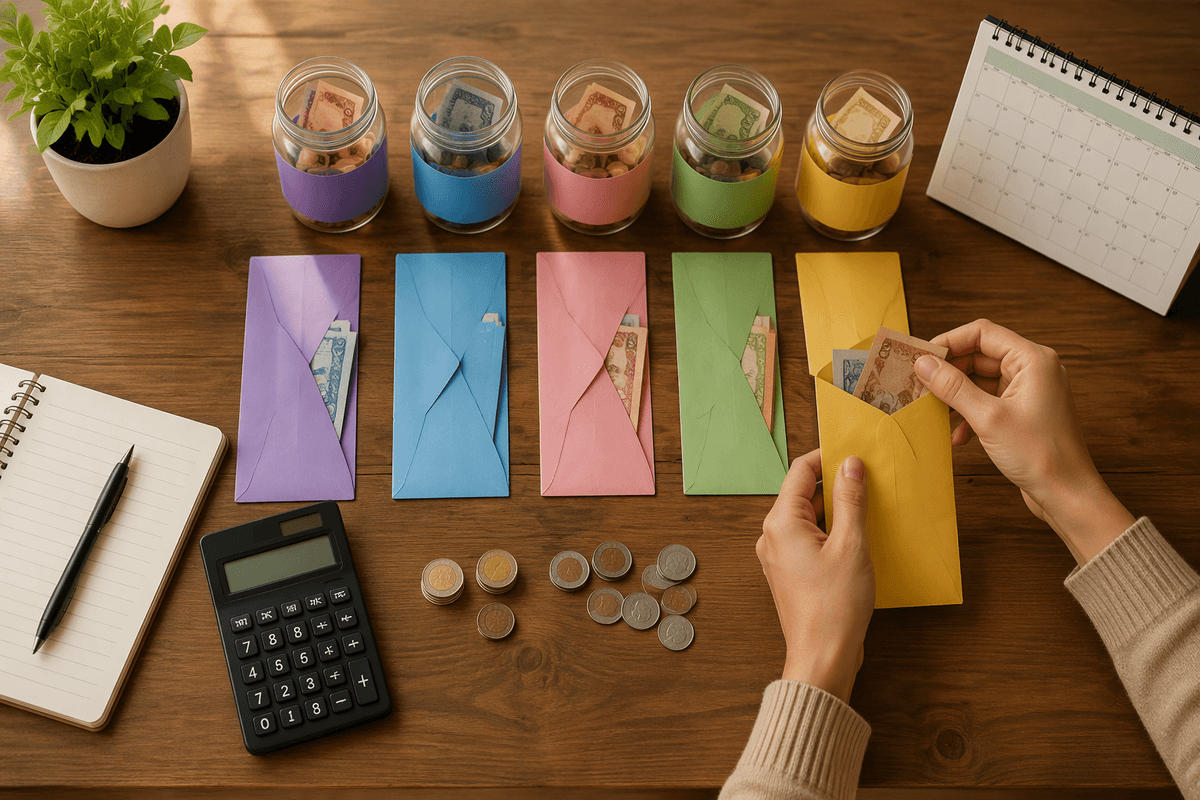
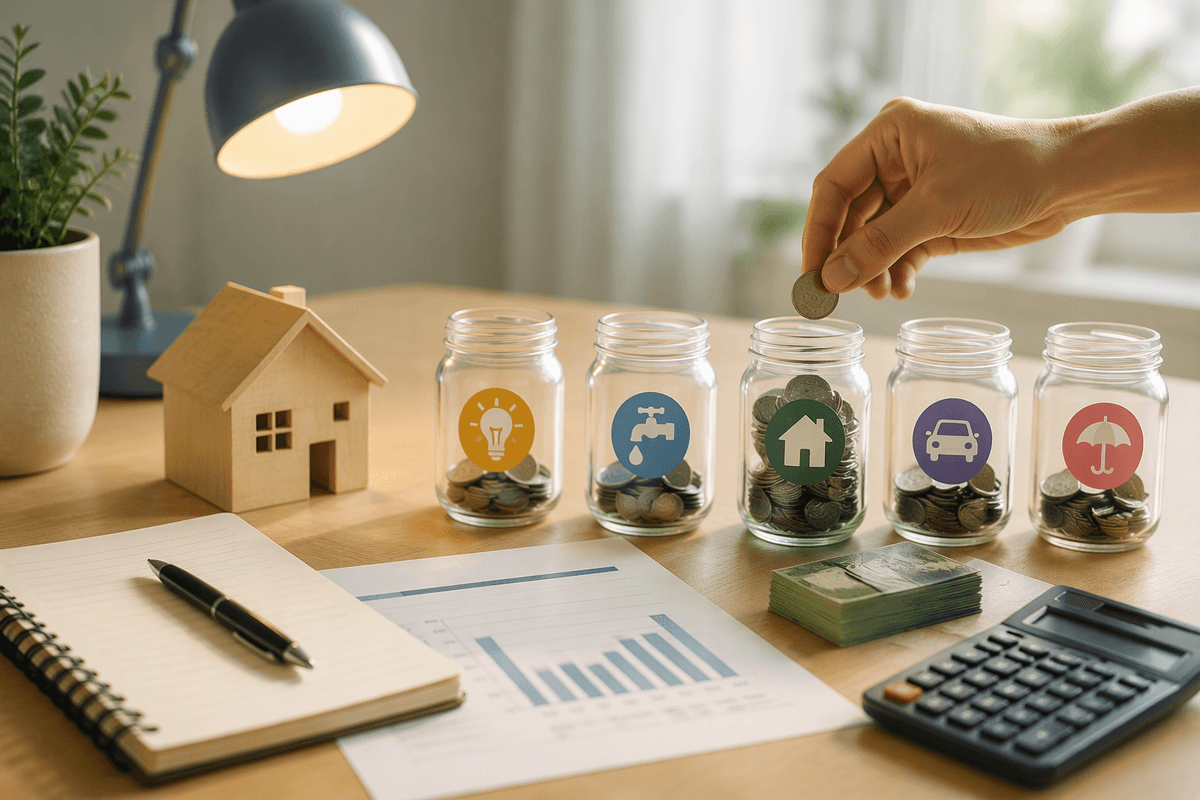
Protecting the reserve for variable bills is easier when irregular costs stop competing with it. Keep separate amounts for expenses such as annual insurance, car registration, school fees, medical deductibles, or holiday travel. Divide each expected cost by the number of months until it is due, then move that amount aside regularly. A $1,200 annual insurance bill becomes a $100 monthly transfer, even though the insurer does not request payment each month.
Separate accounts are useful when timing causes trouble. Money reserved for electricity should not quietly fund a registration fee, and a low-bill month should not be treated as permission to spend the balance. If cash is limited, rank reserves by consequence: protect housing, utilities, insurance, transportation, and obligations with late fees before less urgent goals. The constraint is that several reserves may need funding at once, leaving less available for everyday spending. Start with the costs that are both predictable and disruptive, record the target and due date, and increase the monthly amount after an actual bill shows the estimate was too low.
Adjust Spending After Each Real Billing Cycle
After each bill arrives, compare the estimate with the amount actually charged before changing the rest of the month. A higher electricity bill may reflect weather, a rate change, or a one-time adjustment; a lower bill may simply follow an unusually mild month. Record the reason when it is known, then update the working range rather than reacting to one result. The constraint is timing: a bill may arrive after spending decisions have already been made, leaving little room to correct the month.
Use several billing cycles to decide whether spending can safely move. If the reserve remains intact through high and low months, part of the excess may support groceries, debt payments, or savings. If the reserve is repeatedly used, reduce flexible spending or increase the monthly allocation before the next cycle. Do not treat leftover cash as permanent room until upcoming due dates and irregular reserves are covered. Each real bill makes the next decision less dependent on guesswork.
Use the Pattern to Decide What Is Safe
After several billing cycles, the pattern becomes more useful than any single estimate. A bill that rises only during extreme weather may need a seasonal reserve, while one that stays high across ordinary months signals a permanent budget change. Compare the actual range, the timing of due dates, and how often the reserve was needed. That combination shows whether the current spending level is stable or quietly dependent on low-bill months.
Use that evidence to set boundaries: a minimum cash balance, a monthly reserve contribution, and a spending amount that remains available only after essentials are protected. The constraint is that patterns can change through rates, household needs, or income loss, so safe is never a permanent label. It means the plan has survived the conditions already observed, with enough margin to respond when the next difficult month arrives.