When One Paycheck Stops Feeling Private
A paycheck can feel personal even after a relationship becomes financially serious. One partner may be comfortable sharing every purchase, while the other hesitates when routine spending becomes visible in real time. That hesitation does not always signal distrust. It may reflect different habits, past experiences, or a need to retain some control over money earned independently. Once rent, groceries, debt payments, and savings begin moving through the same system, those preferences become practical rather than abstract.
The first strain often appears in ordinary transactions. A joint account makes bills easier to track and reduces missed payments, but it also makes spending legible to both partners. Separate accounts preserve autonomy, yet require more coordination and can leave one person carrying administrative work. The trade-off becomes sharper when income, debt, or financial risk differs. What feels like convenient transparency to one partner may feel like constant approval-seeking to the other.
The First Comparison: Convenience Versus Control
That trade-off becomes clearer when the account is judged by what it has to do each month. A joint account usually wins on convenience: paychecks can feed one balance, automatic bills draw from the same place, and either partner can see whether the household is on track. The cost is reduced control over timing and discretion. A routine purchase may be financially harmless but still invite questions if both people interpret visibility as oversight.
Separate accounts reverse that balance. Each person keeps clearer control over personal spending and can manage money without explaining every small choice. Coordination becomes the price. Transfers must happen on time, shared costs need a reliable formula, and an overlooked subscription can create a shortfall. Hybrid arrangements sit between the two: common expenses and goals remain visible, while personal money stays partly independent. That can reduce daily friction, but only if the boundaries are specific. Vague rules about what counts as shared spending often produce more negotiation than a fully joint system. The useful comparison is not which structure sounds fairest, but where the household can tolerate inconvenience—and where control is necessary rather than merely preferred.
What Happens When Incomes Do Not Match
Different incomes make a simple split look fair on paper and feel unfair in practice. A 50/50 approach may leave the lower-paid partner with little room after rent, groceries, and debt payments, while the higher-paid partner still has substantial discretionary money. Equal contributions can therefore create unequal pressure, especially when one income is reduced by caregiving, health limits, career changes, or unpaid household work.
Income-based contributions can better match capacity, but they introduce their own friction. The couple must agree on which costs count, whether bonuses and irregular pay are included, and how much each person should retain privately. A joint account funded in proportion to income may handle bills smoothly, yet it can also make the higher earner feel responsible for subsidizing every choice or make the lower earner feel financially dependent. Separate accounts avoid some of that exposure, but the lower-paid partner may still carry greater risk if an emergency arises or a shared goal requires extra cash. The arrangement works only when contribution rules account for both earnings and responsibilities—not just the numbers on each paycheck.
Privacy Changes Meaning After Money Merges
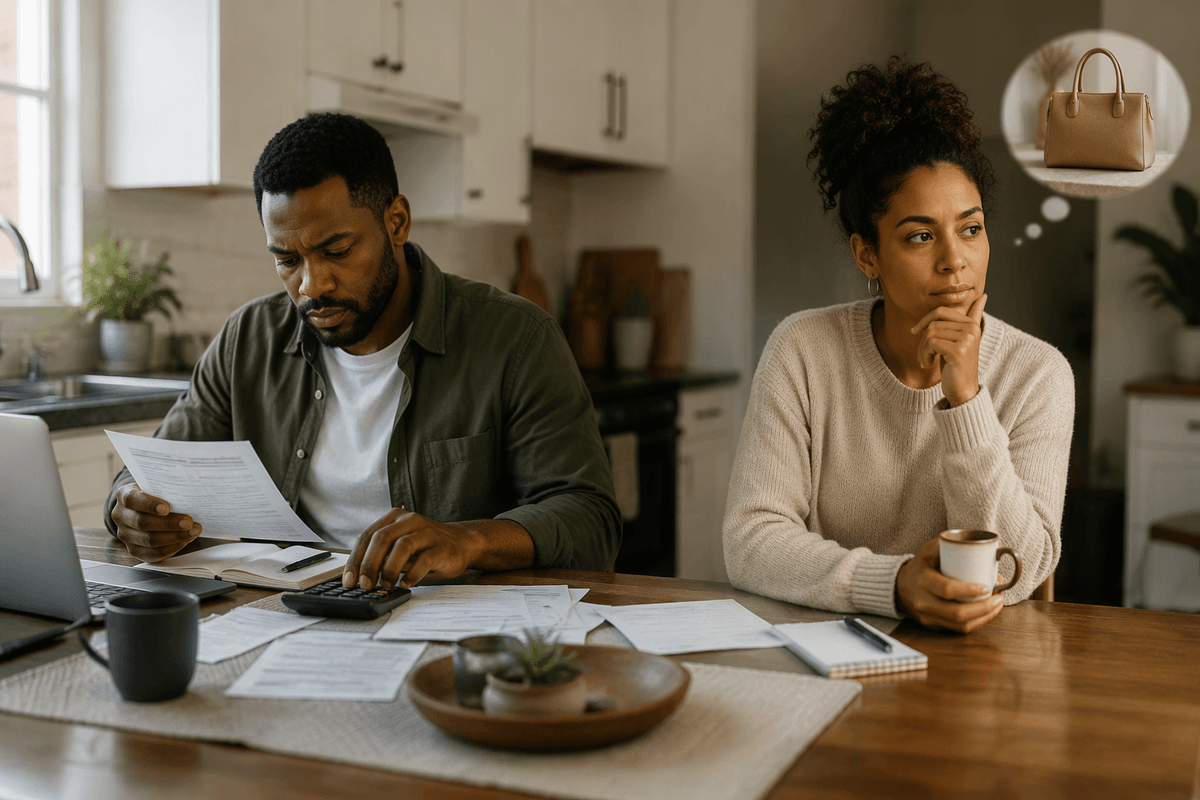
Once contributions are unequal, privacy stops being only a question of hiding purchases. It can affect how each partner experiences dependence, responsibility, and approval. A lower-paid partner may want private money for ordinary choices without feeling monitored, while the higher-paid partner may want visibility because more of the household costs are coming from their income. In a fully joint system, every transaction is easy to inspect, but that visibility can turn routine spending into a measure of fairness.
Separate accounts protect discretion, yet they can also conceal financial pressure. One partner may quietly postpone medical care, build credit-card debt, or avoid mentioning a cash shortfall because the arrangement makes personal problems seem private. A hybrid system often narrows that risk by keeping bills, savings targets, and major debts visible while preserving a limited personal allowance. The constraint is deciding where privacy ends. Without agreed thresholds for disclosure—such as debt, large purchases, or account balances—privacy can protect autonomy one month and undermine trust the next.
Why Volatile Months Expose Weak Arrangements
The arrangement is tested most clearly when income or expenses stop behaving normally. A commission-based paycheck, seasonal work, unpaid leave, medical bill, or major repair can make a previously comfortable split unreliable. In a joint system, the shortfall is visible immediately, which helps the household adjust but may also create pressure if one partner expects the other to cover the gap without discussion. Separate systems preserve independence until a shared bill is due, then the lack of available cash becomes an urgent coordination problem.
Hybrid structures can absorb some volatility by directing a set amount toward essentials while leaving the rest under personal control. That method still depends on timing. If income arrives late, automatic withdrawals may trigger overdraft fees before either partner notices, and a fixed contribution may no longer reflect actual capacity. The stronger arrangement is not necessarily the one that works during an average month. It is the one with a clear response when earnings fall, costs jump, or one person temporarily cannot contribute as planned.
The Hybrid Model Resolves Some, Not All, Tension
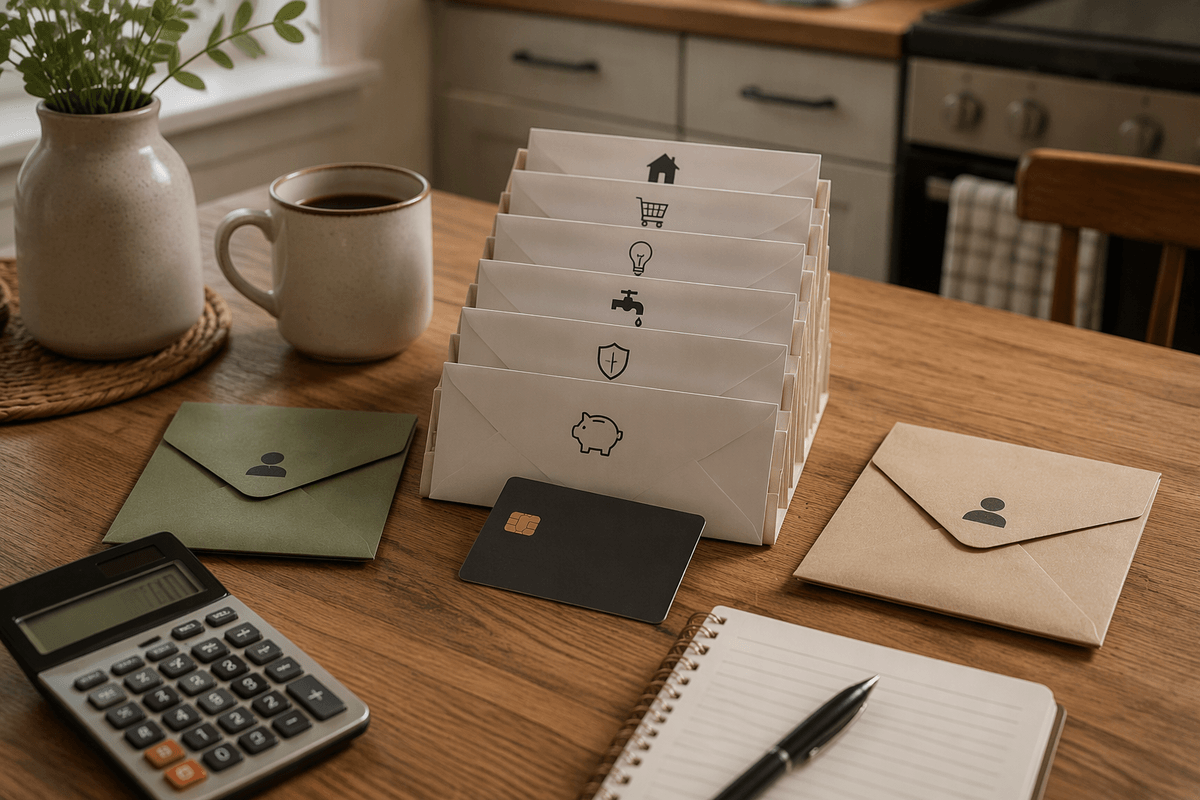
That response plan is where a hybrid arrangement earns its appeal. Shared income can cover rent, utilities, groceries, insurance, and agreed savings, while each partner keeps a defined amount for personal spending. The structure reduces the need to inspect every transaction and gives the household one place to monitor obligations. It also makes income-based contributions easier to apply when earnings differ. The compromise has a practical limit, though: the shared transfer must be large enough for real expenses without leaving either person dependent on repeated top-ups.
Unclear boundaries can recreate the same conflict in a less visible form. Couples still need to decide whether dining out, gifts, subscriptions, debt payments, and irregular repairs belong to the common account. They also need a rule for surplus money and a response when one partner spends the personal allowance faster than the other. Too much shared money can feel controlling; too little can turn bill-paying into monthly negotiations. A hybrid model therefore reduces tension only when its limits are deliberate, reviewed after income changes, and backed by enough shared cash to handle ordinary surprises.
Choose Rules Before Choosing the Account
By this point, the account itself is the easier decision. The harder one is agreeing what it should make possible, what it should keep separate, and who absorbs the strain when circumstances change. A joint, separate, or hybrid setup can all work, but each fails when expectations remain unwritten. Automatic transfers, shared bills, personal allowances, emergency funding, and disclosure thresholds need decisions before balances start moving.
A short trial period can expose practical weaknesses without turning the choice into a permanent verdict. Review the arrangement after an irregular month, a major expense, or a change in income. The best structure is not the one that removes every disagreement. It is the one that makes responsibilities visible, preserves reasonable autonomy, and gives both partners a workable response when the numbers no longer cooperate.