A resignation date can trigger several benefit deadlines
A resignation can look like one clean date on a calendar, but the financial effects rarely follow that same line. A final paycheck may arrive weeks later, health coverage may continue through the end of a month, and a retirement match may depend on when the last contribution is made. Meanwhile, a flexible spending account or paid-time-off balance may follow entirely different rules. That uneven timing creates practical decisions before the next employer’s benefits begin.
The first step is to list each benefit separately and ask what event controls it: the resignation date, the last day worked, the final paycheck, or the end of the coverage month. Missing even one deadline can mean paying a higher premium, losing access to funds, or facing a temporary coverage gap.
The date you leave is not when everything ends
That date becomes only the first marker. Health coverage may remain active through the last day of the month, while dental or vision coverage could stop on the last day worked. A final paycheck may also include deductions for benefits that were earned earlier, making the net amount smaller than expected. The exact timing often depends on the employer’s plan documents rather than the resignation letter.
Other benefits can move in the opposite direction. Paid time off may be paid with the final wages, carried over only in limited circumstances, or forfeited under company policy. A flexible spending account may stop accepting new reimbursements after employment ends, even though eligible expenses occurred while coverage was active. Retirement contributions may continue through the final payroll, but an employer match or vesting credit could depend on that payroll’s processing date. Treating the departure date as a universal cutoff can therefore create both unnecessary costs and missed opportunities. Each benefit needs its own end date, action date, and confirmation.
Your next health coverage choice starts with a deadline
Once the current plan’s end date is confirmed, the next decision is governed less by preference than by the first deadline that arrives. A continuation notice may offer the same employer plan for a limited period, but the election window can begin before the next job’s benefits are available. A marketplace plan may follow a different enrollment period, while a spouse’s plan may require action soon after the loss of coverage. Waiting for the new employer’s orientation can leave a household paying out of pocket or temporarily uninsured.
Cost estimates also need to include more than the monthly premium. Continued employer coverage may preserve familiar doctors and deductibles, but the full premium can be much higher once the employer contribution disappears. A new individual plan may cost less each month yet carry a narrower network, a higher deductible, or different prescription rules. The practical comparison is between the coverage needed during the gap and the date each option must be elected, not simply between advertised premiums. Request the exact termination date, election deadline, first payment date, and effective date in writing. A missed payment or late election can matter more than a small difference in monthly cost.
Compare the premium against the protection
The lower monthly premium can look persuasive until the first prescription, specialist visit, or emergency claim exposes what the plan leaves behind. A continuation option may cost more because it preserves the existing deductible, network, and out-of-pocket progress. That matters when treatment is already underway or a family member has regular appointments. The higher bill is not automatically wasteful; part of it may be paying to avoid a new deductible during a short transition.
A cheaper plan can still be the better bridge when the household expects little medical care and the gap will last only a few weeks. But the comparison should use likely spending, not the premium alone. Check the deductible, out-of-pocket maximum, prescription tiers, provider network, and whether current claims will carry over. A plan with a $300 monthly premium may become more expensive than a $700 option after one uncovered medication or out-of-network visit. Timing adds another constraint: the first premium may be due before reimbursement or the next paycheck arrives. Set aside enough cash for that payment and compare the worst plausible cost, not just the ordinary month.
Unused time and spending accounts need separate answers
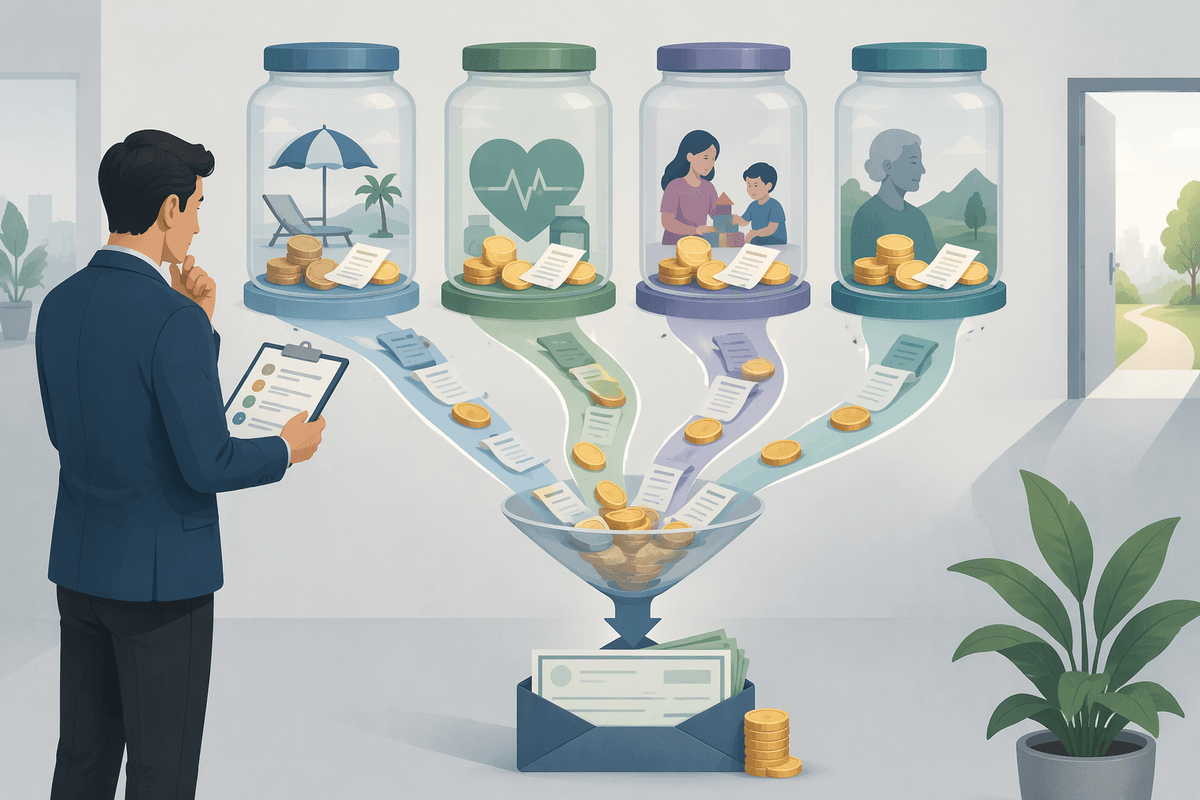
The same final paycheck can contain two very different answers about unused benefits. Paid time off may be paid out, carried over, or lost under the employer’s policy and the applicable state rules. That makes the balance on a payroll screen less useful than a written explanation of what will appear in the final check and when it will be paid. A delayed payout can also affect cash available for the first health premium after leaving.
Spending accounts require a separate review. A health flexible spending account may allow reimbursement for eligible expenses incurred before coverage ends, but claims usually must be submitted by a stated deadline. Dependent-care funds may follow different rules, and unused amounts can be forfeited if the expense or claim arrives too late. A health savings account generally remains the employee’s money, though employer contributions may stop with the final payroll. Before departure, save account instructions, check remaining balances, and confirm the last eligible expense date. Assuming every account follows the same cutoff can turn available funds into a missed reimbursement.
Retirement money keeps moving after your paycheck stops
Retirement accounts do not usually stop changing on the last day worked. Contributions may still appear after departure because the final payroll has not yet been processed, and an employer match may be based on that payroll rather than the resignation date. A statement showing new money after leaving is not necessarily an error. It may reflect deductions already taken from wages or a delayed deposit.
The next decision is what happens to the account itself. A former employer’s plan may allow the balance to remain, but investment choices, administrative fees, and withdrawal rules can differ from a new employer’s plan or an individual rollover account. Moving the money too quickly can create tax complications, while leaving it unattended can mean missing higher fees or losing track of old accounts. Check vesting, the final contribution date, outstanding plan loans, and rollover instructions before requesting a transfer. A loan that becomes due after departure can create an unexpected tax bill if it is not repaid on time.
Build a bridge until the next benefits package
The gap between jobs is easier to manage when it is treated as a short financial bridge rather than an empty stretch on the calendar. List the expected dates for the final paycheck, health coverage end, continuation election, first premium, and new employer enrollment. Then reserve cash for premiums, prescriptions, doctor visits, and regular household bills that may arrive before the next paycheck. A delayed start date or waiting period can turn a planned two-week gap into several months.
Keep important records accessible during the transition: plan notices, account balances, claims information, provider contacts, and confirmation numbers. If coverage depends on a spouse’s plan or a marketplace enrollment, verify the effective date instead of relying on an application receipt. The bridge does not need to preserve every former benefit, but it should prevent one missed deadline from becoming a larger bill or an avoidable lapse in protection.
Leave with a timeline, not assumptions
By the time the next benefits package becomes available, several earlier decisions may already be irreversible. Coverage could have ended, an election window could be closing, or a final paycheck may have arrived smaller than expected because of deductions. A written timeline turns those moving parts into specific tasks: confirm each benefit’s end date, record every election deadline, and mark when money must be paid.
Keep the timeline with the plan notices and confirmation numbers, then check it against the first paycheck and enrollment statement from the new employer. Assumptions about “continuous coverage” or automatic account transfers are costly when dates differ. The transition may still involve higher premiums or a temporary waiting period, but the uncertainty narrows once each benefit has a documented answer and an assigned next step.